Convertible Bond Values
Compare exchange values.
Estimated reading time: 1 minute
Investor.gov distinguishes fixed conversion formulas from market-linked formulas. A convertible bond can exchange into common shares; its face amount is not necessarily its resale value.
Compare two values
Assume one fictional $1,000 bond currently permits optional conversion into exactly 40 shares, surrendering the bond. Ignore interest, fees and taxes. All prices below are hypothetical immediately executable values.
At $22 per share, conversion produces stock worth 40 × $22 = $880. If selling the bond instead brings $970, conversion leaves $90 less value.
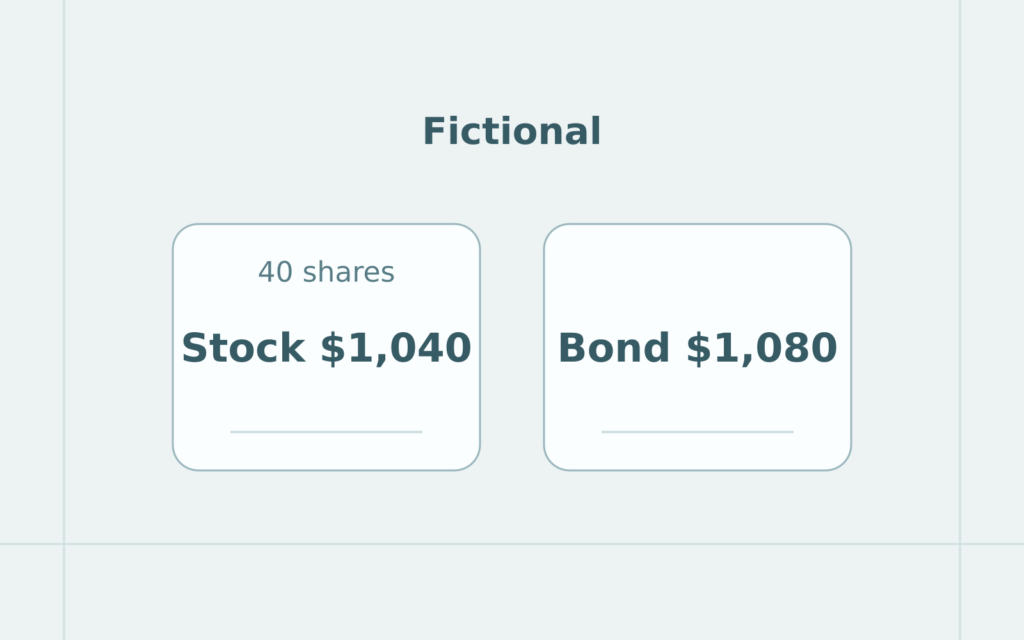
In a separate scenario, shares trade at $26 and the bond at $1,080. Conversion produces $1,040, still $40 less than selling the bond. Exceeding the $25 implied conversion price ($1,000 ÷ 40) does not settle that comparison.
Check the actual terms
Conversion exchanges the bond, not merely its interest: do not also count its $1,000 principal. Confirm eligibility, share ratio, settlement provisions and actual sale proceeds. Prices can change before execution. This comparison is neither a conversion recommendation nor a return calculation.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.