Employee Stock Purchase Sale Allocation
Separate compensation from capital gain.
Estimated reading time: 1 minute
Meeting an employee stock purchase plan’s holding periods does not necessarily make every dollar of profit capital gain.
Completed purchase and sale
Consider a fictional qualifying statutory plan and nontransferable option. The employee remained employed throughout grant and exercise. On January 1, 2022, the employer granted an option for 100 shares at a fixed $20 each; grant-date fair value was $22. Exercise and share transfer occurred July 1, 2023. The employee sold all shares September 1, 2025, for their $30-per-share fair value, with no fees or adjustments.
Allocate the profit
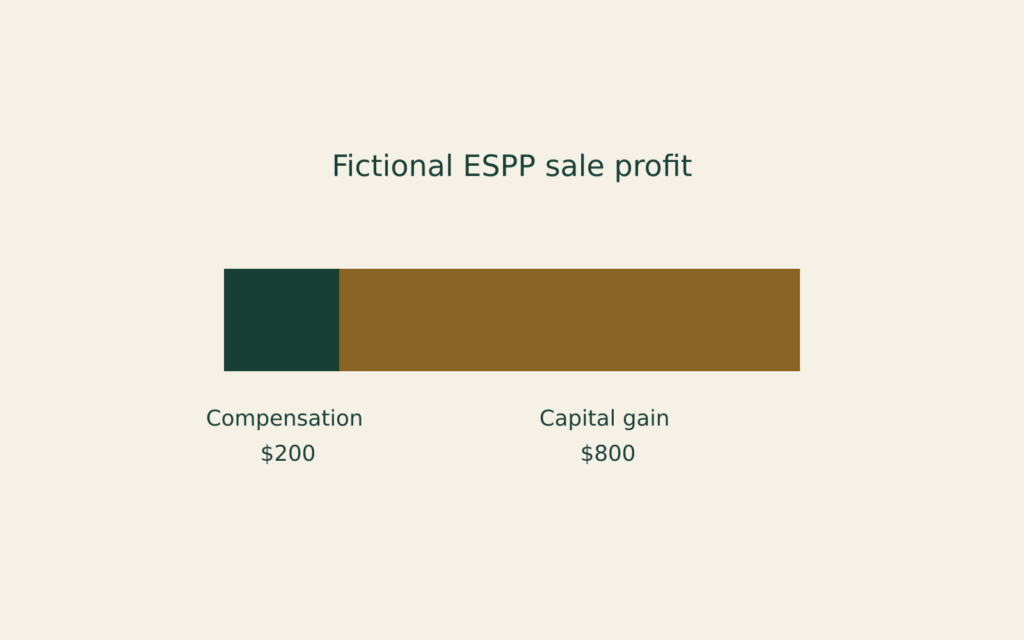
Both holding periods exceed Publication 525’s requirements: two years after grant and one after transfer. Compensation is the lesser of the $2 grant discount and $10 sale appreciation per share: $200 total. The remaining $800 is capital gain.
The $3,000 receipt therefore comprises $2,000 purchase cost, $200 compensation and $800 capital gain—not $1,000 entirely capital gain. This does not calculate total tax or validate a broker’s reported basis.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.