IRA Basis Across Two Accounts
An untouched traditional IRA can affect the nontaxable portion of another IRA’s distribution.
Estimated reading time: 1 minute
An untouched traditional IRA can affect the nontaxable portion of another IRA’s distribution.
Use both year-end records
Assume a 65-year-old original owner, alive throughout 2025, has only two traditional individual retirement accounts (IRAs), neither SEP nor SIMPLE. Verified unrecovered nondeductible basis entering 2025 is $1,000. The only 2025 transaction is a routine $2,000 cash withdrawal from A—not a special distribution. There are no contributions for 2025, rollovers, conversions, recharacterizations, repayments or other basis adjustments.
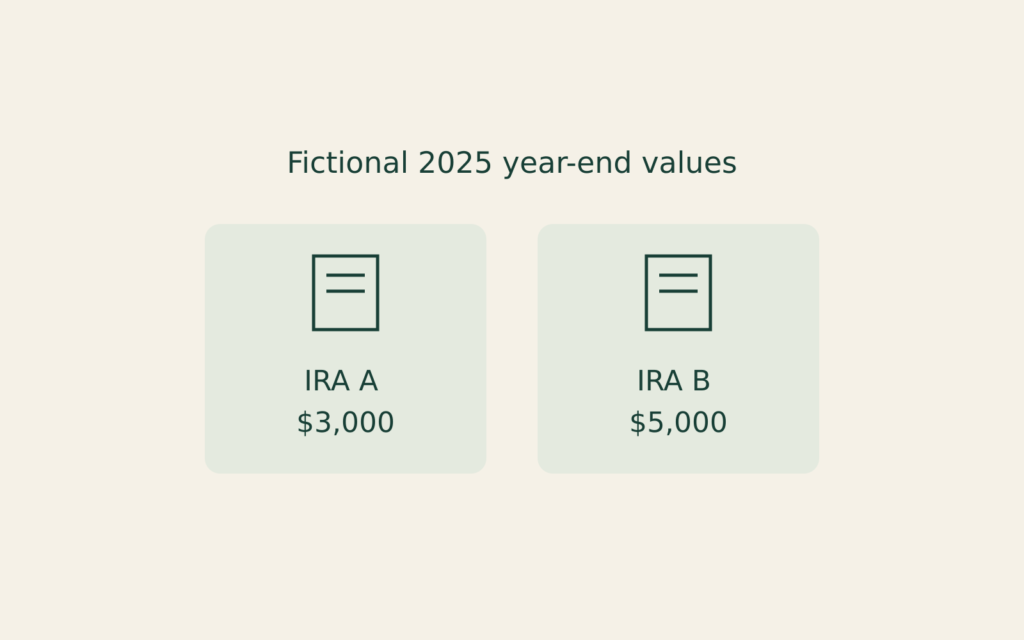
December 31, 2025 values are $3,000 in A and $5,000 in B. B made no distribution.
2025 Form 8606 combines the year-end values with the distribution here: $3,000 plus $5,000 plus $2,000 equals $10,000. The basis fraction is $1,000 divided by $10,000, or 0.100. Multiplying the $2,000 distribution by 0.100 gives $200 nontaxable; remaining unrecovered basis is $800.
Omitting B would overstate that fraction. The $1,000 basis is not automatically withdrawn first. This limited allocation example does not calculate total tax or recommend a withdrawal.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.