IRA Excess Across Years
Track excess contribution balances.
Estimated reading time: 1 minute
Unused IRA contribution room can absorb an earlier excess without erasing the earlier year’s additional tax.
A fictional single U.S. taxpayer is under 50 throughout 2024–2025, earns $50,000 taxable wages each year, and has no workplace retirement coverage. They own one ordinary traditional IRA, with no other IRA contributions or special adjustments.
They contribute $8,000 for 2024 and $6,000 for 2025, each by December 31. No earlier excess exists, no 2024 excess was deducted, and no withdrawal, rollover, recharacterization or later contribution occurs. Year-end IRA values exceed $1,000 in both years.
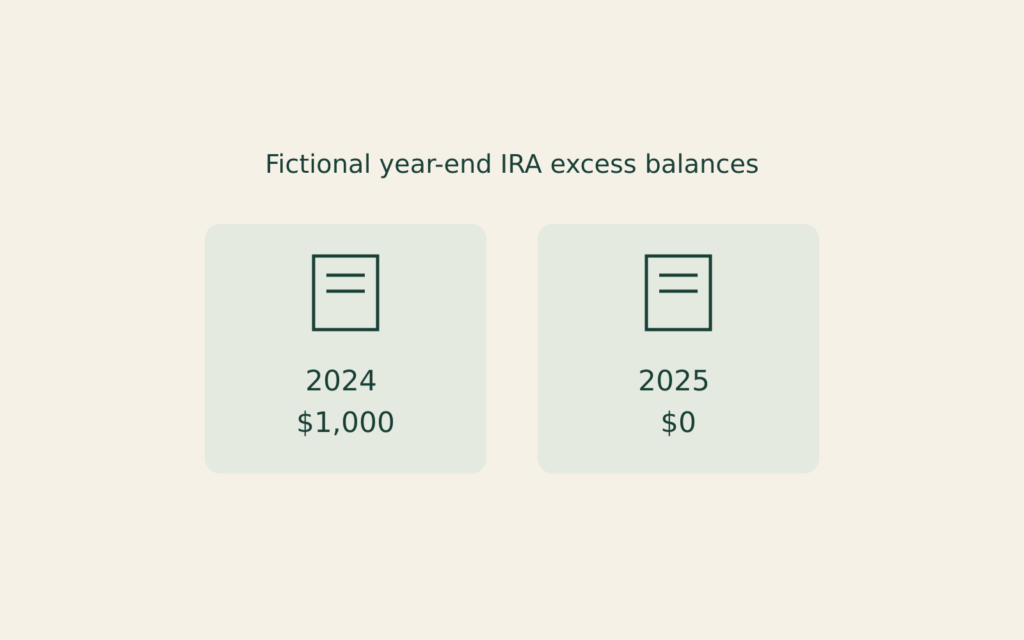
Publication 590-A (2025) explains the $7,000 limits and later-year application. The 2024 excess is $1,000, producing $60 additional tax at 6%; the account-value cap does not reduce it.
For 2025, unused room is $7,000 − $6,000 = $1,000. Applying the carried excess fills that room and leaves zero excess subject to 2025’s 6% tax.
This is not a second cash contribution or a refund of 2024’s $60. Track both contribution years separately.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.