ISO Dual-Basis Records
Reconcile exercise and sale adjustments.
Estimated reading time: 1 minute
The same incentive-option shares can carry different regular-tax and alternative-minimum-tax (AMT) bases.
A fictional employee receives a qualifying nontransferable ISO on January 1, 2022: 100 shares at $10 each, their grant-date fair value. Employment continues through exercise. Nothing is paid for the option.
On January 2, 2024, the employee pays $1,000 and receives all shares, immediately transferable with no forfeiture risk. Their fair value is $3,000. All are held through year-end.
Under Publication 525 and the Form 6251 instructions, exercise creates no regular-tax income but a $2,000 positive AMT adjustment. Regular basis is $1,000; AMT basis becomes $1,000+$2,000=$3,000.
All shares sell November 1, 2025, for $3,500. Both holding periods are satisfied: over two years after grant and one after transfer. No fees, other dispositions, capital-loss carryovers or adjustments apply.
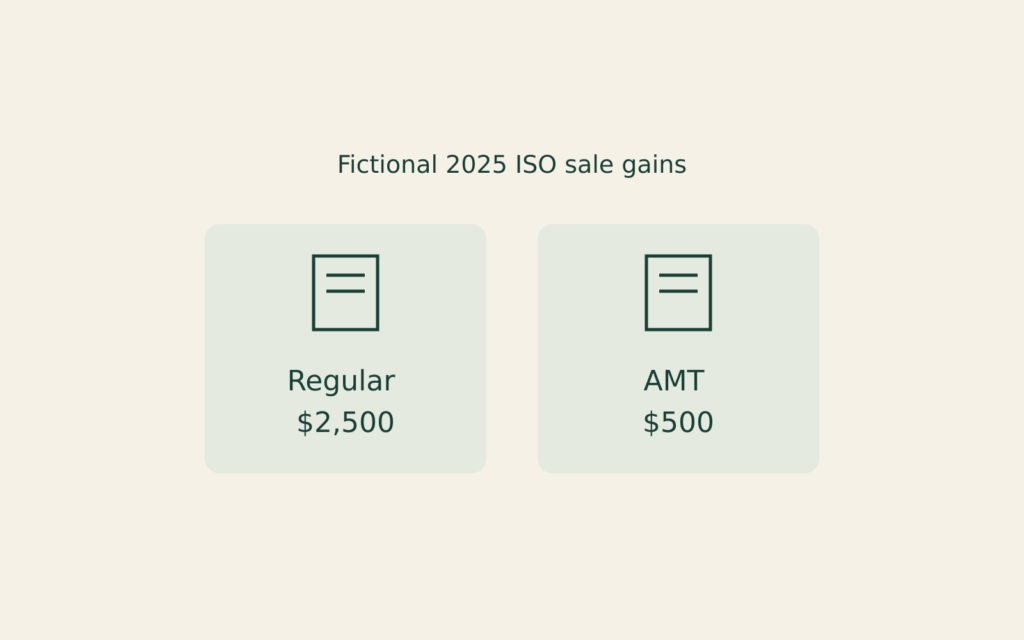
Regular long-term gain is $2,500; AMT long-term gain is $500. The sale therefore produces a negative $2,000 AMT adjustment—not a refund or tax credit. Final AMT liability and any credit remain separate.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.