Loan Counteroffer Dates
Separate offer expiry.
Estimated reading time: 1 minute
Regulation B separates a credit counteroffer’s acceptance window from the creditor’s adverse-action notification timing.
Read the actual expiry
Fictional consumer personal-loan applicant requests $12,000. On November 3, the lender instead offers $8,000, expressly expiring November 10. The applicant neither accepts nor uses the offered credit.
The rule’s 90-day notification provision does not require the lender to keep that offer open for 90 days. Do not treat it as an acceptance extension.
Check what accompanied the offer
- Counteroffer without a compliant combined adverse-action notice: if the applicant does not expressly accept or use the offered credit, adverse-action notification is required within 90 days after counteroffer notification.
- Counteroffer with a compliant combined adverse-action notice: another adverse-action notice is not required merely because the applicant does not accept.
Keep the original request, counteroffer, stated expiry and accompanying notices together. Ask the lender which terms remain available before relying on them.
This example does not calculate a legal deadline or determine notice compliance. An $8,000 counteroffer also leaves the original $12,000 funding need unresolved; approval is not affordability.
Changing Loan Autopay: Check the Notice
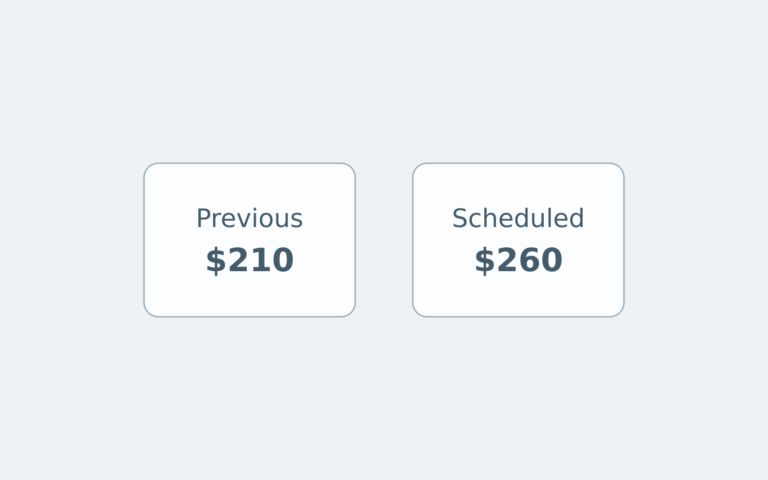
Compare the debit and notice.
Approved for a Loan, but Received a Risk-Based Pricing Notice?
Identify the document and separate report-review questions from the actual loan offer.
Paycheck Loan Reserve: Annual Share or Half the Bill?
Compare two reserve allocations without changing the lender’s payments.