Loan Offsets and Withholding
Reconcile the cash.
Estimated reading time: 1 minute
The IRS includes an eligible plan-loan offset in the 20% withholding base, but limits withholding to the accompanying cash and eligible property.
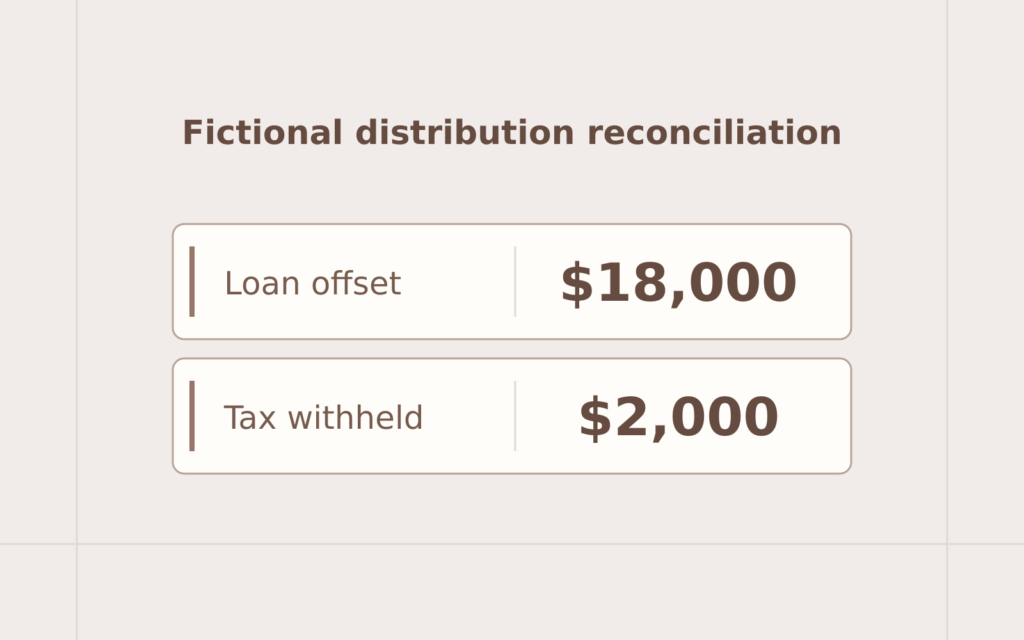
Fictional employer-plan distribution: an $18,000 loan offset and $2,000 cash distributed simultaneously. Assume pre-tax funds, eligible rollover distributions, no direct rollover, no prior deemed distribution and no other property.
The withholding base is $18,000 + $2,000 = $20,000. Twenty percent is $4,000, but only $2,000 cash is available. Required withholding is therefore capped at $2,000, leaving zero cash for the participant.
Using only cash as the base incorrectly produces $400 withholding and $1,600 spendable cash.
The correct record reconciles $20,000 as $18,000 offset plus $2,000 withheld, not $20,000 deposited. The offset reduces the retirement benefit to repay the loan; it is an actual distribution.
Capped withholding is not a reduced final tax bill or proof that the distribution is tax-free. Ask the administrator to confirm classification and amounts, then review rollover eligibility, replacement funding and deadlines separately. This example determines neither tax liability nor a rollover deadline.

Parent Pays Student Loan Interest: Who Deducts?
Separate payment and obligation.

Returned Loan Debit: Two Fees?
Trace the payment and fees.

Rehabilitation Payment Too High?
Check an alternative request.