Mortgage Credit and Deduction
Credit and deduction differ.
Estimated reading time: 1 minute
Mortgage credits can reduce deductions by more than the credit currently usable.
A fictional single homeowner itemizes for 2025. Their state issued a valid qualified mortgage credit certificate (MCC) under its qualified program for their solely owned main home within that state’s jurisdiction. The original purchase mortgage is entirely within the certified indebtedness; the certificate rate is 25%.
They pay $10,000 of otherwise fully deductible 2025 mortgage interest to an unrelated bank. No refinancing, other mortgages, subsidies, refunds, prior credit carryovers or other credits apply. The completed credit-limit worksheet establishes $1,200 available tax.
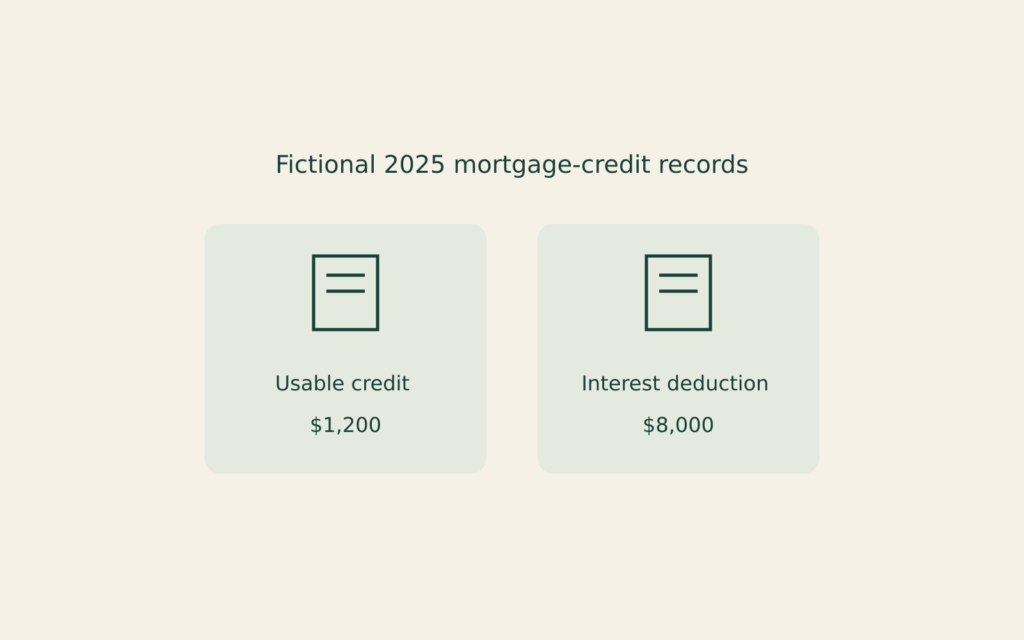
2025 Form 8396 starts with $10,000×25%=$2,500, but the over-20% rate caps line 3 at $2,000. Only $1,200 is currently usable; $800 carries forward for up to three years, subject to future limits. The $500 above the cap cannot carry forward.
The interest deduction falls by the full $2,000 line-3 amount—even though $800 carries—leaving $8,000, not $8,800. Credit, carryforward and deduction are separate records, not a final refund or total tax calculation.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.