Partial Wash Sale: Replacement Basis
Match shares and loss portions.
Estimated reading time: 1 minute
A partial wash sale can leave a current sale loss while increasing replacement-share basis.
Match shares, then reconcile basis
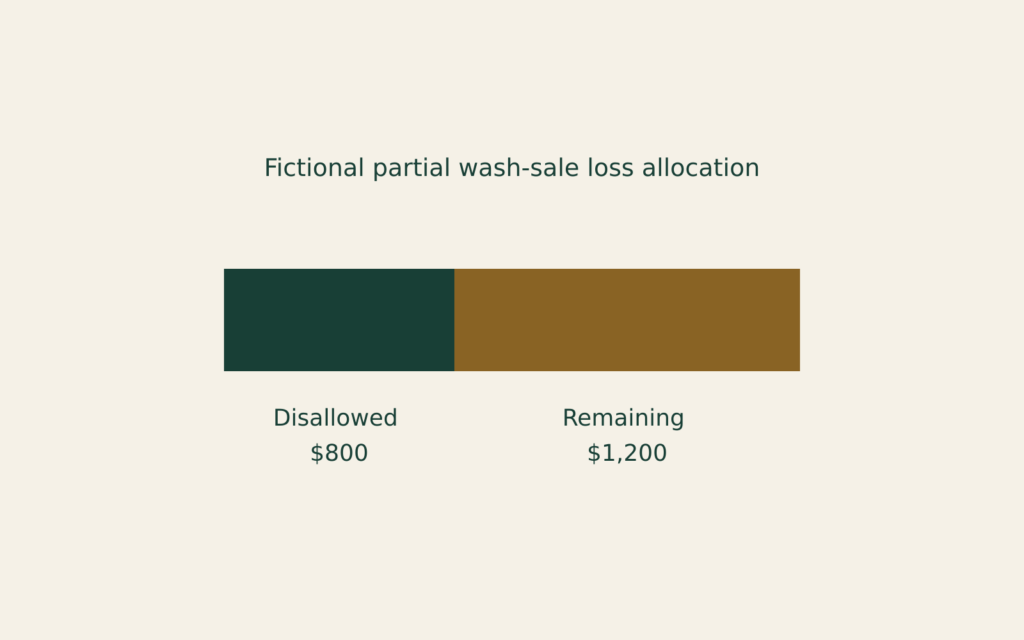
A fictional U.S. nondealer investor bought one 100-share lot of ordinary corporate stock for $10,000 in September 2024. On January 6, 2025, they sold all shares for $8,000. On January 21, they bought 40 identical shares for $3,200, retaining them. Both trades use taxable brokerage accounts, with no fees, other basis adjustments, options or special arrangements. No other substantially identical acquisitions occurred within 30 days before or after the sale, including through retirement accounts, a spouse or controlled corporation.
Publication 550 matches replacement purchases to an equal number sold. The $2,000 loss is $20 per share: 40 matched shares disallow $800; $1,200 remains outside this wash-sale disallowance.
Add $800 to the replacement lot’s $3,200 cost: its basis becomes $4,000, not its cash purchase price. This calculates neither net deductible loss nor tax savings and recommends no trade.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.