Purchased Bond Interest: Seller Component
A full bond coupon can include an amount the buyer already paid to the seller.
Estimated reading time: 1 minute
A full bond coupon can include an amount the buyer already paid to the seller.
Match the purchase and coupon
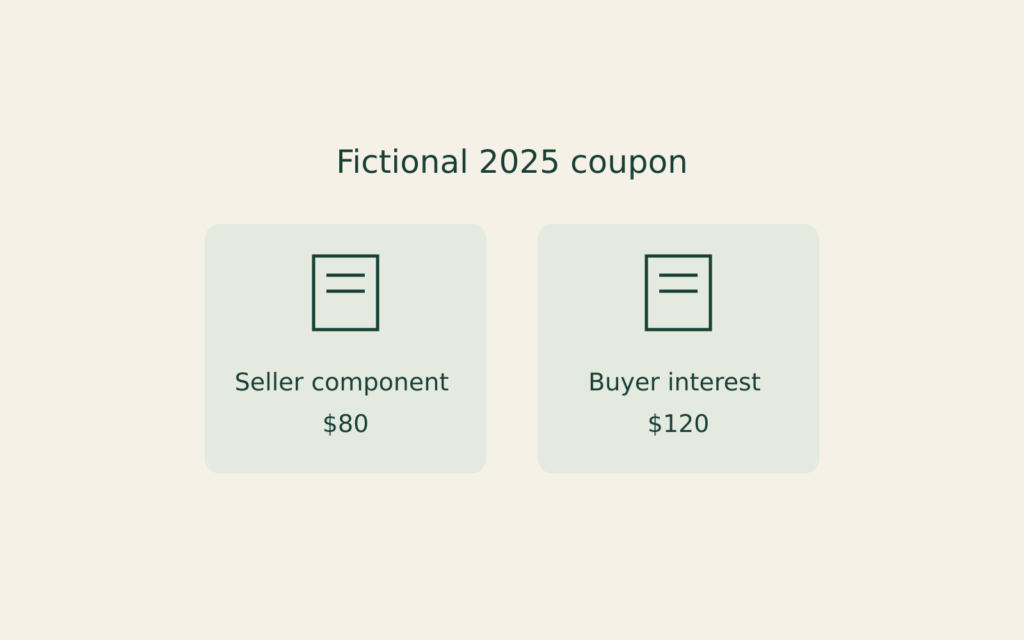
Consider an individual’s fictional 2025 purchase, in a taxable account, of an ordinary taxable coupon bond between interest-payment dates. The settlement record separately identifies $80 paid to the seller for accrued interest. Later that year, the buyer receives the next $200 coupon, and Form 1099-INT includes the full $200. Assume no premium, discount, fees or other adjustments.
The relevant interest reconciliation is $200 minus $80, or $120—not a deduction of the bond’s entire purchase price.
Keep the seller component separate
IRS Publication 550 (2025) explains that accrued interest paid to the seller is taxable to the seller, not the buyer. Its receipt returns that part of the buyer’s capital investment and reduces bond basis.
Keep the settlement breakdown with the coupon and tax form. This example does not calculate total bond basis, investment return or a personal tax bill.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.