QCDs: RMD and Income Records
Reconcile distributions against two records.
Estimated reading time: 1 minute
An IRA distribution can count toward a required minimum distribution without entering taxable income.
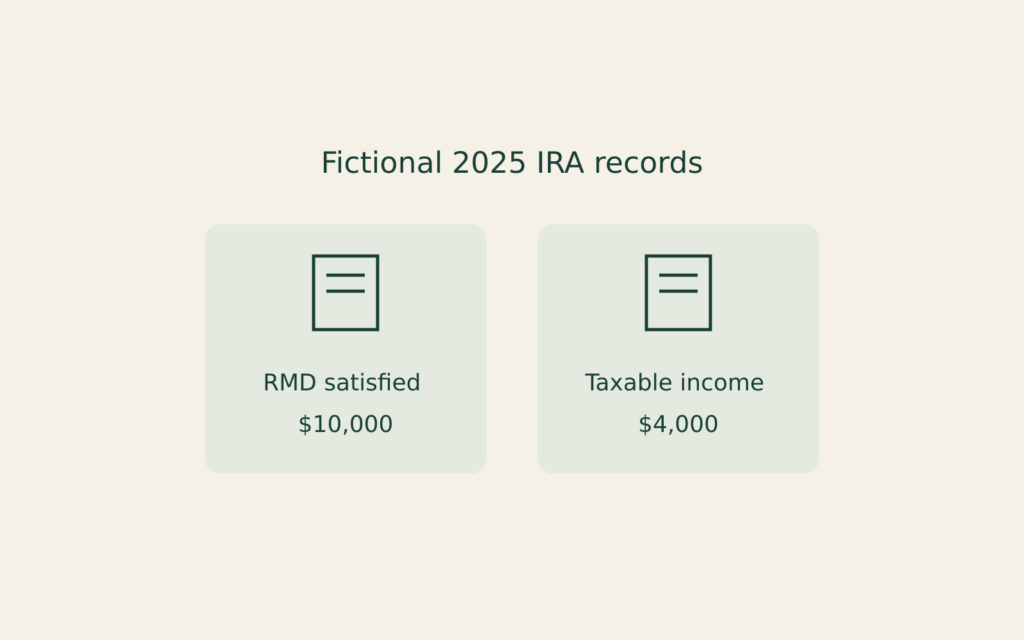
Fictional 2025 records
A 75-year-old original owner has one ordinary traditional IRA, entirely pretax—not a SEP or SIMPLE IRA. The calculated 2025 required minimum distribution (RMD) is $10,000.
In November, the trustee pays $6,000 directly to a public charity whose QCD eligibility is verified. The owner receives no benefits and holds the required charitable acknowledgment. In December, the owner receives a $4,000 ordinary distribution.
No other distributions, split-interest gifts, deductible IRA contributions at age 70½ or older, or adjustments apply.
Under Publication 590-B (2025), the $6,000 qualified charitable distribution (QCD) counts toward the RMD and is excluded from income. Together, $6,000 + $4,000 satisfies $10,000; only the $4,000 distribution enters income.
The excluded $6,000 cannot also support a charitable deduction. Match the trustee’s payments and charity’s acknowledgment to both records: RMD completion is not the same as taxable IRA income. No tax or donation recommendation follows.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.