Salary Deferrals Across Plan Types
Compare completed 2024 contribution records.
Estimated reading time: 1 minute
Two employers do not automatically provide two independent salary-deferral limits.
Compare completed 2024 records
Consider alternative fictional histories for a 40-year-old employee with two unrelated employers. Verified eligible compensation is $50,000 at each. There are no catch-up provisions, employer contributions, other additions, other plans or special adjustments; each plan permits the stated amounts subject to legal limits.
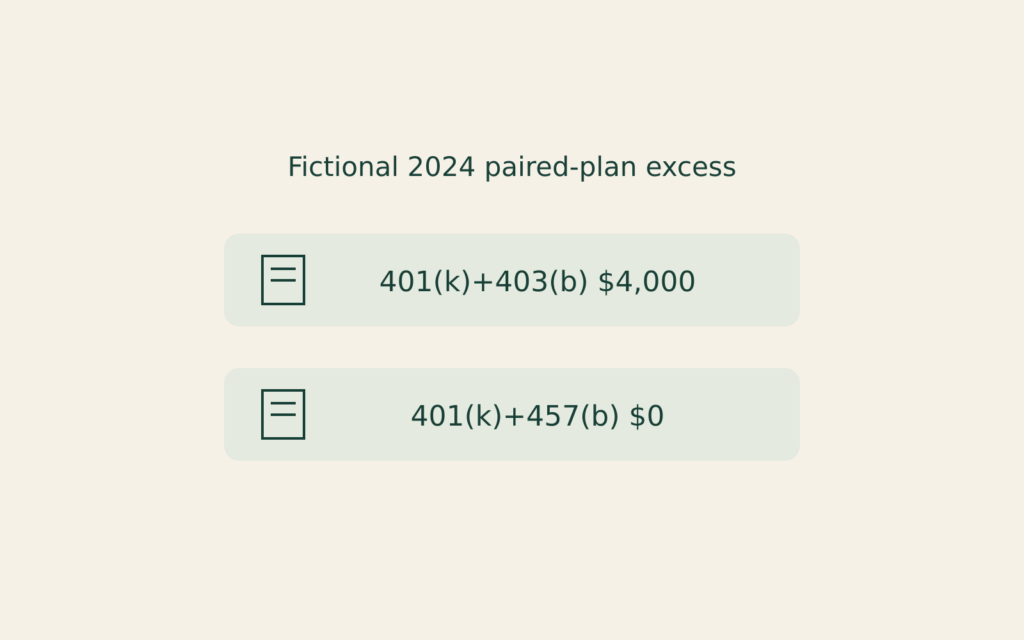
- A: $15,000 deferred to a 401(k) and $12,000 to a 403(b).
- B: $15,000 deferred to a 401(k) and $12,000 to an eligible governmental 457(b).
IRS guidance combines 401(k) and 403(b) deferrals. A’s $27,000 exceeds the 2024 $23,000 individual limit by $4,000. The 457(b) limit is separate and includes employer contributions. In B, $15,000 and $12,000 are separately below their $23,000 limits and compensation amounts.
The same $27,000 total therefore answers different limit tests. Confirm plan classifications and all contributions before combining records. This comparison does not calculate matching, tax savings, withdrawal access or an excess-correction procedure.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.