Solar Loans: Low Rates, Higher Principal
Compare solar-loan prices and remaining debt, not just the rate.
Estimated reading time: 2 minutes
Compare solar-loan prices and remaining debt, not just the rate.
Keep the installation identical
The FTC recommends detailed written bids covering system output, installation costs, guarantees and warranties. Resolve differences before comparing financing.
The CFPB’s August 2024 report described financed-price markups; it does not establish today’s charges.
Fictional matched installation: A borrows the $24,000 cash price at 8%; B borrows a $30,000 financed price at 3%. Both have zero down payment and 120 monthly payments, starting one month after funding. Rates are fixed nominal annual rates divided by twelve, not disclosed APRs. There are no other charges or extra payments.
- Monthly payment: A $291.19; B $289.68.
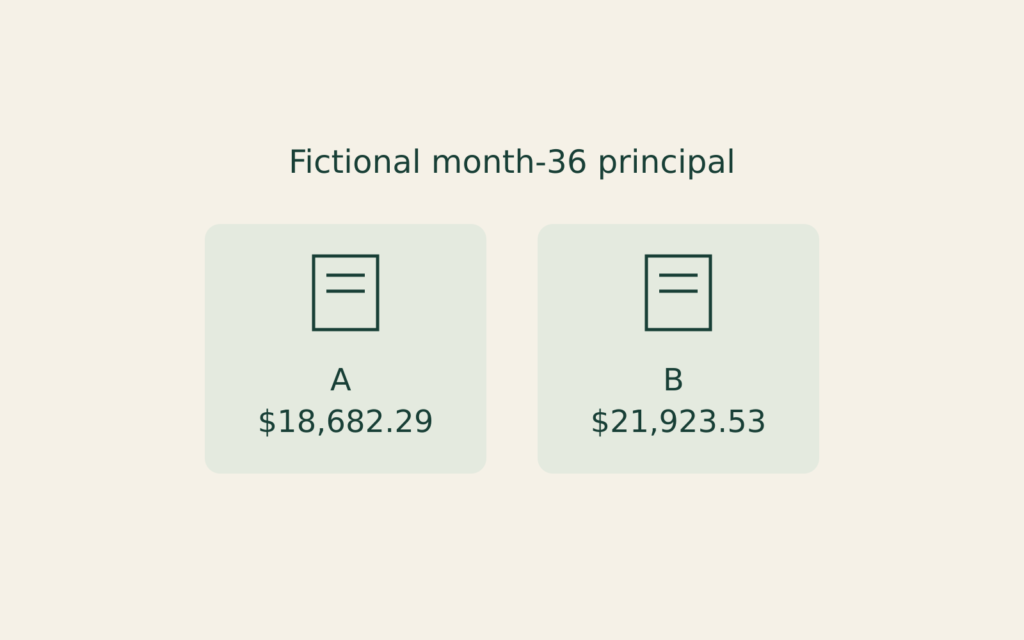
- Principal after payment 36: A $18,682.29; B $21,923.53.
B’s slightly smaller payment leaves more debt at that checkpoint. Full-precision calculations are rounded for display; these balances are not payoff quotes or a full-term cost ranking.
Exclude an unverified tax benefit
No tax benefit or electricity savings offsets either example. IRS FAQs 1 and 7 say the section 25D credit is unavailable for expenditures after December 31, 2025. Original installation completion determines an item’s expenditure timing, not earlier payment. Construction or reconstruction has a separate original-use timing rule.

Parent Pays Student Loan Interest: Who Deducts?
Separate payment and obligation.

Returned Loan Debit: Two Fees?
Trace the payment and fees.

Rehabilitation Payment Too High?
Check an alternative request.