SSI: A Shared Income Exclusion
Reconcile wages and pension income.
Estimated reading time: 1 minute
SSI’s general income exclusion is shared across income types; it is not a separate $20 allowance for every source.
Consider a fictional single adult’s ordinary 2026 month: $885 gross wages and a $100 gross private-pension payment, both regularly received. Apart from SSI, these are the only income. The person is not a student or blind; there is no deemed income, in-kind support, impairment-related work expense, self-support plan or other special exclusion or adjustment.
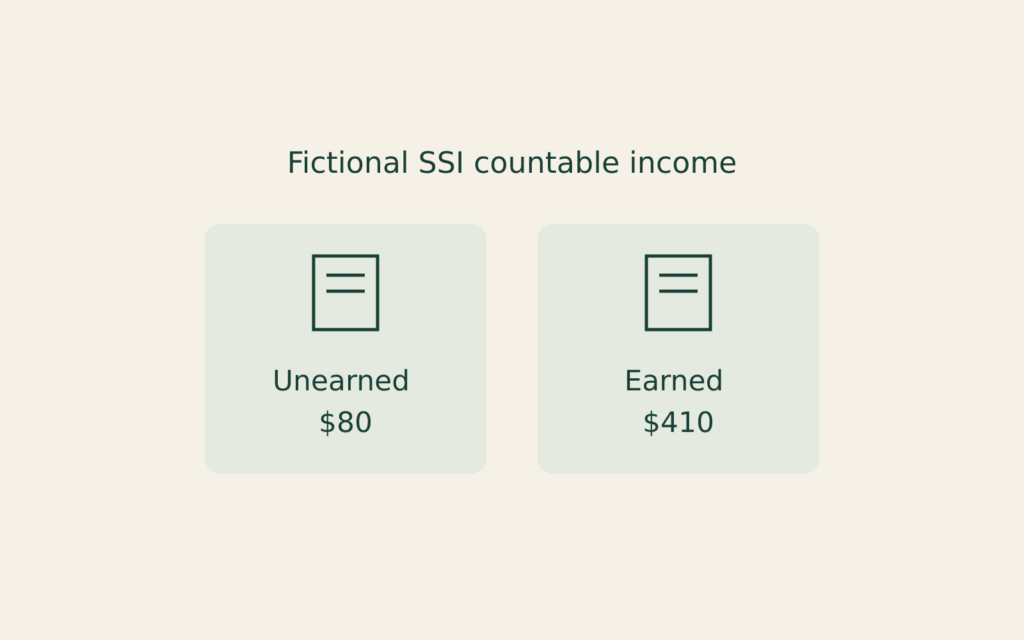
SSA’s exclusions first remove $20 from the unearned pension income, leaving $80 countable. None of that exclusion remains for the wages. Subtract the earned-income exclusion of $65 from $885, then exclude half the $820 remainder: $410 is countable earned income.
Total countable income is $80+$410=$490—not $480 from using the general exclusion twice. This reconciles the income calculation, not the bank balance. Keep the gross payment records and exclusions separate. The example does not determine SSI eligibility, resources, the payment month or the final benefit amount.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.