Private Student Loans: In-School Payment Choices
Compare three fictional $9,000 student-loan schedules and see why $810 paid early produces a $198.86 modeled difference in total cost.
When comparing private student loan payment choices, separate the cash required now, interest accumulating unpaid, and any later addition of that interest to principal. Those are different parts of the schedule. A low required payment can fit today’s budget while leaving a larger balance for later.
The CFPB explains capitalization as adding unpaid interest to principal, after which interest is charged on that larger principal. Accrued interest is already owed before that event. Ask which events trigger capitalization under your private loan’s contract; interest accrual and capitalization are not the same thing.
Check which choices your actual loan offers
Private loans have their own payment-start rules. Check your documents or servicer, including how any grace period treats interest. Do not assume every loan provides the same payment-free interval.
As one provider example, Sallie Mae lists deferred, fixed and interest repayment for specified undergraduate and graduate products, with exceptions for residency/relocation and bar-study loans. Its page says interest begins at disbursement; options can have different rates. For its stated fixed and deferred choices, unpaid interest is added to principal at the end of the grace/separation period. These terms are product-specific.
The example below holds the rate constant to isolate payment timing. It is not Sallie Mae’s pricing or a claim that every lender offers all three choices. Obtain figures for the options actually available to you.
A fictional experiment with one $9,000 disbursement
Assume $9,000 is provided at the outset at a fixed 9% nominal annual interest rate. There are twelve equal monthly school periods, followed by sixty equal principal-and-interest payments beginning in month 13. There are no fees, discounts, further disbursements, missed payments or rate changes.
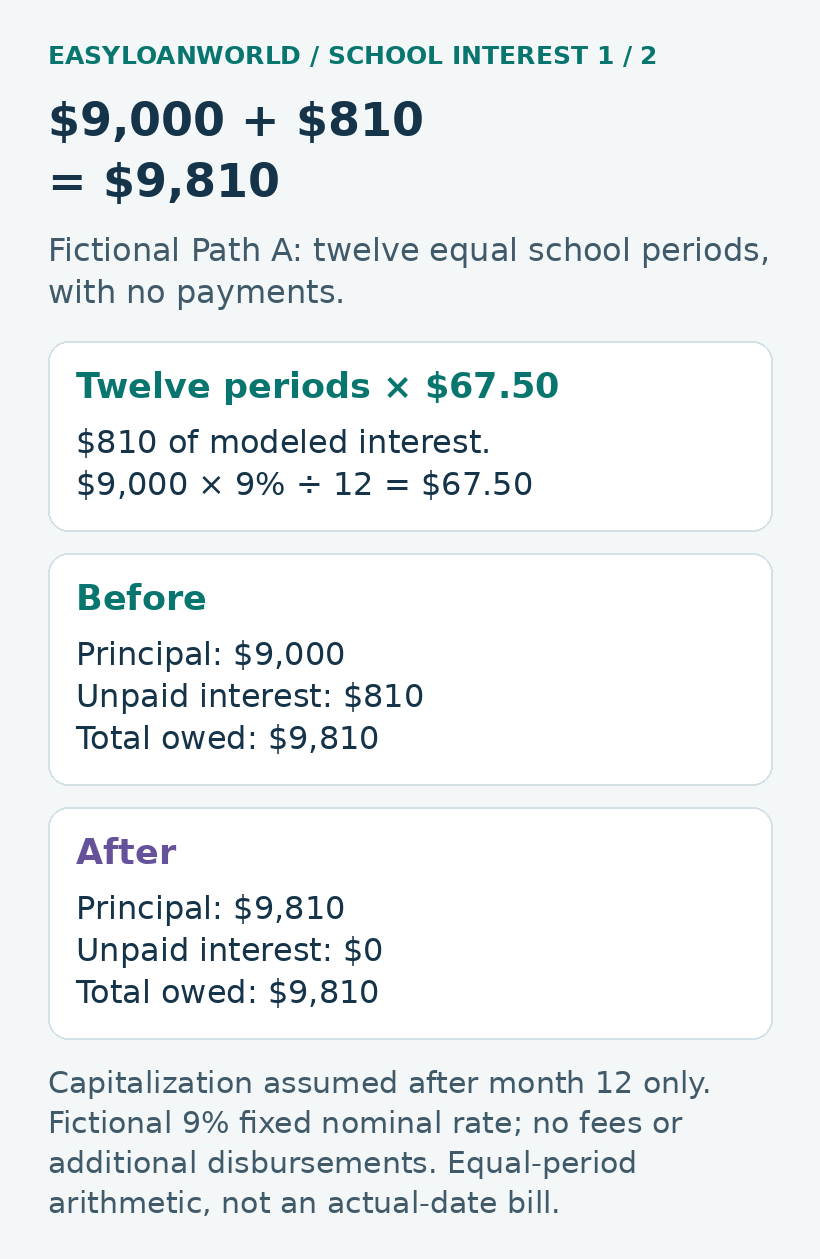
For this model, monthly interest is $9,000 × 9% ÷ 12 = $67.50. During the first twelve periods, interest does not capitalize monthly. Payments apply to unpaid interest first. At the end of month 12, after that month’s payment if applicable, any remaining unpaid interest capitalizes once.
This capitalization date is an invented contract assumption. The three paths have the same rate and later term; actual quoted options may differ. All totals use unrounded installments before rounding to cents, so displayed payment amounts may not multiply exactly. An actual schedule may adjust its final payment.
Path A: make no payments during the twelve school periods
- Cash paid during school: $0
- Before capitalization: $9,000 principal plus $810 unpaid interest, totaling $9,810 owed
- After capitalization: $9,810 principal, still totaling $9,810 owed
- Next monthly-model interest: approximately $73.58
- Later installment: approximately $203.64
- Sixty later payments and all-period outflow: $12,218.37
- Total interest above the $9,000 provided: $3,218.37
Path B: pay a fixed $30 each school month
- Cash paid during school: $360
- Unpaid interest after month 12: $810 − $360 = $450
- Before capitalization: $9,000 principal plus $450 unpaid interest
- After capitalization: $9,450 principal, without a new disbursement
- Next monthly-model interest: approximately $70.88
- Later installment: approximately $196.17; sixty later payments total $11,769.99
- All-period outflow, including the earlier $360: $12,129.99
- Total interest: $3,129.99
Every required $30 payment is made, but it does not cover the model’s $67.50 monthly interest. The unpaid amount therefore grows by $37.50 each month. “Fixed payment” describes the payment amount here; that label alone would not establish an actual loan’s interest-rate type.
Path C: pay the full $67.50 monthly-model interest
- Cash paid during school: $810
- Unpaid interest at the assumed capitalization date: $0
- Principal remains $9,000
- Next monthly-model interest: $67.50
- Later installment: approximately $186.83; sixty later payments total $11,209.51
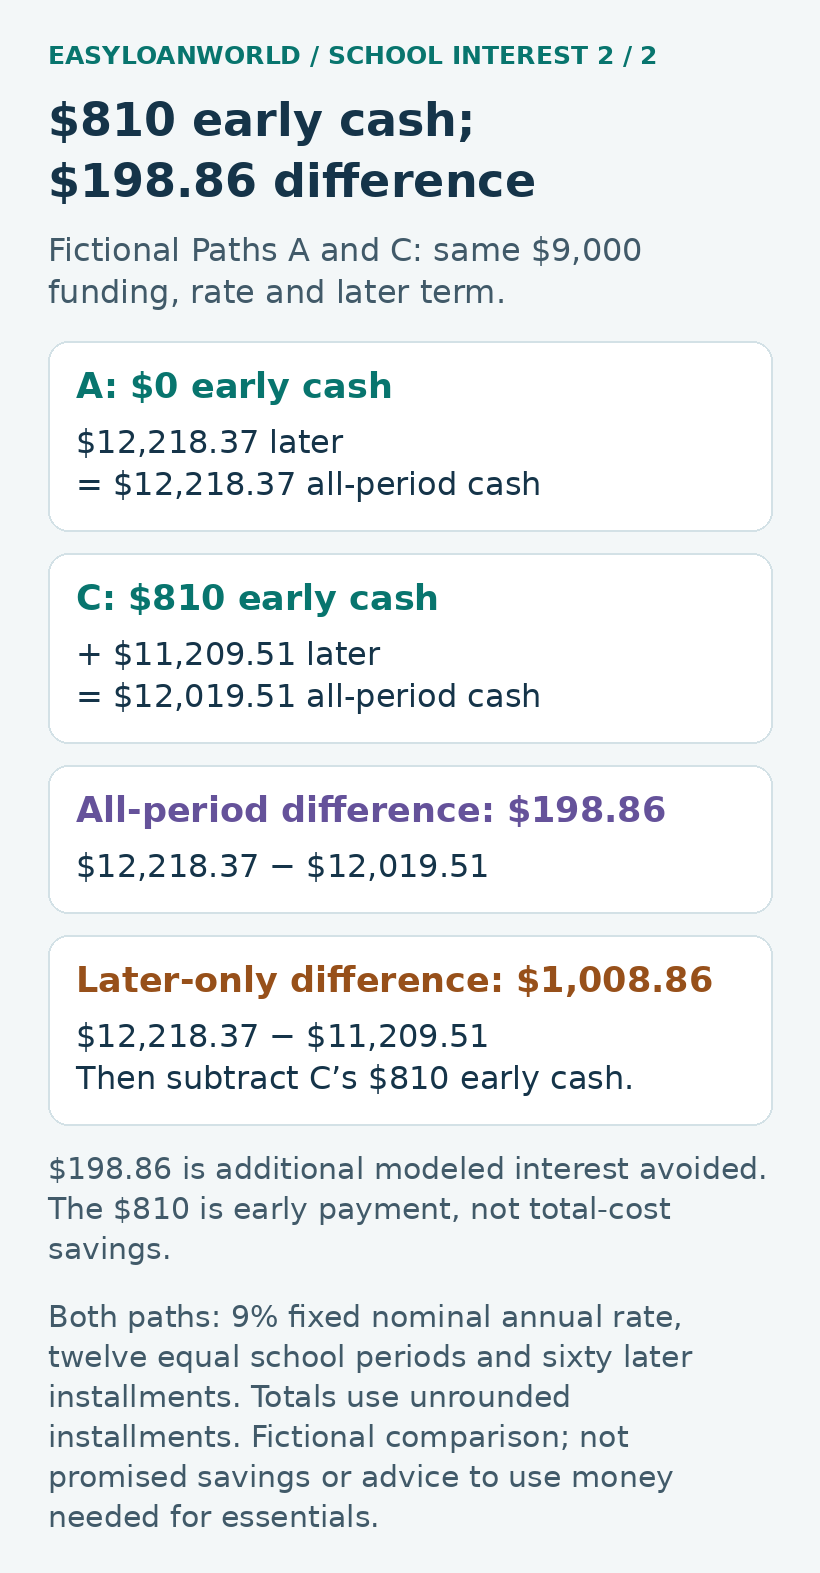
- All-period outflow, including the earlier $810: $12,019.51
- Total interest: $3,019.51
Paying $810 early does not create $810 of total-cost savings. It pays interest already accruing. Compared with Path A, Path C removes $810 from the later starting principal and avoids approximately $198.86 of additional modeled interest on that amount.
The all-period difference is $12,218.37 − $12,019.51 = $198.86. Comparing only the later-payment totals would leave out the $810 paid earlier. These are fictional cash flows, not promised savings or a recommendation to use money needed for essentials.
Why a fixed dollar payment may miss actual interest
The main example uses equal monthly periods. For a separate sensitivity check, assume actual/365 daily interest on the same $9,000 at 9%, with no intervening changes:
- 30 days: $9,000 × 9% × 30 ÷ 365 ≈ $66.58
- 31 days: $9,000 × 9% × 31 ÷ 365 ≈ $68.79
A $67.50 payment leaves approximately $1.29 unpaid after that hypothetical 31-day period, assuming interest-first allocation and no fees or prior interest. Do not mix these daily figures into the equal-month totals above. Actual bills depend on the contract’s dates, balance, rate, accrual and rounding method.
A daily accrual method does not, by itself, mean interest becomes principal every day. Verify capitalization separately.
Make one option-and-date card
Keep a separate card for each offered option, with a document reference beside each answer:
- Product, document version and selected option
- Required school-period cash, any separation/grace-period payments, and the first later payment date
- Principal, unpaid interest and total owed, shown separately; capitalization trigger and expected amount
- Option-specific rate and conditions; later payment estimate and total including early payments
- Whether an option change is allowed, what changes if enrollment changes, and the written response reference
Date each answer and preserve the supporting document. Leave an unknown entry open instead of carrying an assumption from another product into this card.
If you want a different option, ask about permission, timing and revised figures before treating a change as approved. An informational question does not authorize a payment pause. Keep using confirmed instructions while resolving what would change.
Check cash flow during school and when the later payment begins. The lower modeled cost is useful only alongside a plan you can sustain. Keep your statements privately; if figures do not reconcile, ask which dates, balances and payment entries were used. This card records instructions and questions, not a replacement bill.
Featured photo: Blank stationery for tracking education costs. Photo: Cht Gsml / Unsplash. Used under the Unsplash license.
Before You Compare 401(k) Access: Three Document Checks
Use three situation-specific cards to organize documents and prepare questions before comparing 401(k) access.
College Withdrawal Bill: Reconcile the School Account
Use three school records and a fictional $1,340 example to trace each adjustment, check a changed balance and organize questions for the right office.
Student Aid Credit Balance: Separate the School Ledger From Spendable Cash
Use two fictional aid snapshots and a private payment record to organize the amounts, permissions and dates behind a college-account credit.