Temporary Buydowns: The Payment Path
Mortgage subsidies and year-three payment pressure.
Under Fannie Mae’s rules, a temporary buydown leaves the note unchanged. Qualification uses the note rate; you remain liable if subsidy funds fail. This fixed-note example is not an ARM reset or permanent discount points.
Start with the payment in year three. In the invented example below, someone who can spare $1,800 a month for principal and interest has room during the first two years, then faces a $96.20 monthly shortfall. A temporary head start does not repair that ongoing mismatch.
Build the $300,000 example
Assume a $300,000 mortgage at a fixed 6.5% annual nominal interest rate, repaid over 360 equal monthly periods. The first installment is one month later. There are no financed fees, extra payments or late payments. Taxes, insurance, mortgage insurance, association charges and other ownership costs sit outside this principal-and-interest calculation and can change.
For this invented 2-1 arrangement, calculate the borrower’s first-year contribution using $300,000, 4.5% and 360 months, and the second-year contribution using $300,000, 5.5% and 360 months. Starting in month 25, use the 6.5% calculation. Assume an eligible third party funds the entire subsidy and no separate charge is imposed on the buyer in this illustration; this does not establish that a real offer is free.
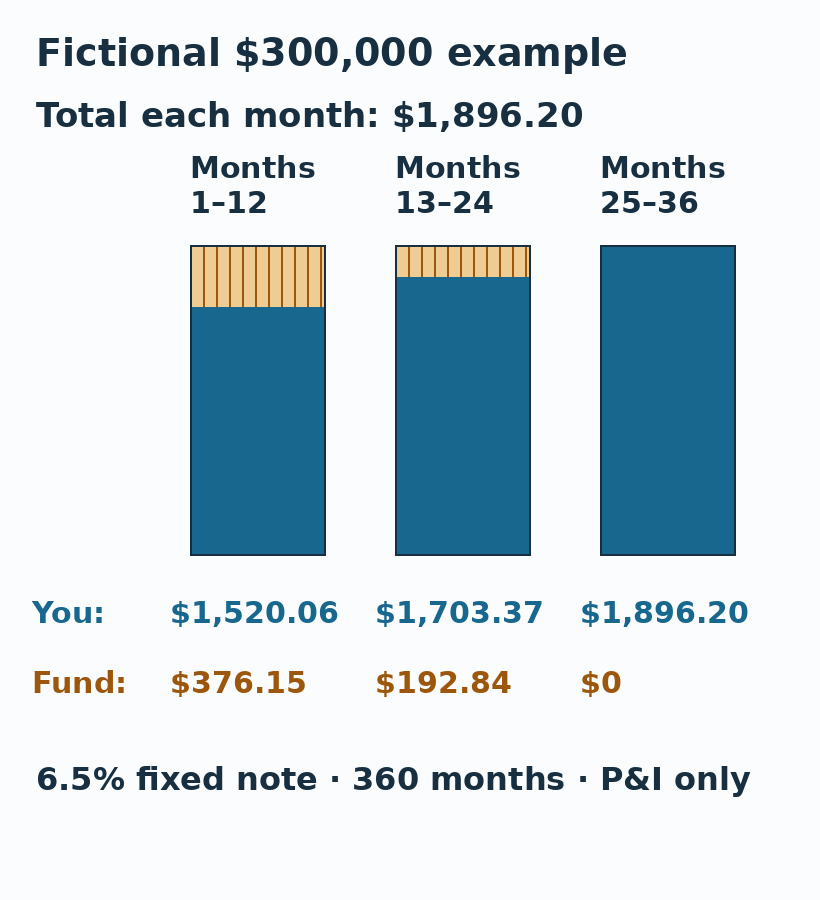
The monthly payment formula is P × r ÷ [1 − (1 + r)−n], where P is principal, r is the annual nominal rate divided by 12, and n is the number of months. It produces $1,896.20 at 6.5%, $1,520.06 at 4.5% and $1,703.37 at 5.5%.
The subsidy covers the difference. In this model that is about $376.15 monthly for 12 months, then $192.84 monthly for 12 months. Adding the 24 unrounded differences gives $6,827.82 of initial funding. Months 25–36 use none.
| Period | You contribute | Fund contributes | Combined |
|---|---|---|---|
| Year 1 | $1,520.06 | $376.15 | $1,896.20 |
| Year 2 | $1,703.37 | $192.84 | $1,896.20 |
| Year 3 | $1,896.20 | $0.00 | $1,896.20 |
Follow every payment through month 36
The table applies monthly interest of 6.5% ÷ 12 to the opening balance, then subtracts the full calculated installment. In month one, interest is $1,625.00 and principal repayment is $271.20. The next month’s interest uses the resulting balance. Values are independently rounded; totals retain precision, so multiplying the displayed subsidies overstates the modeled fund by six cents. This is not a cent-rounded servicing ledger.
| Month | Borrower contribution | Subsidy contribution | Full installment | Balance, either version |
|---|---|---|---|---|
| 1 | $1,520.06 | $376.15 | $1,896.20 | $299,728.80 |
| 2 | $1,520.06 | $376.15 | $1,896.20 | $299,456.12 |
| 3 | $1,520.06 | $376.15 | $1,896.20 | $299,181.97 |
| 4 | $1,520.06 | $376.15 | $1,896.20 | $298,906.34 |
| 5 | $1,520.06 | $376.15 | $1,896.20 | $298,629.21 |
| 6 | $1,520.06 | $376.15 | $1,896.20 | $298,350.58 |
| 7 | $1,520.06 | $376.15 | $1,896.20 | $298,070.44 |
| 8 | $1,520.06 | $376.15 | $1,896.20 | $297,788.79 |
| 9 | $1,520.06 | $376.15 | $1,896.20 | $297,505.60 |
| 10 | $1,520.06 | $376.15 | $1,896.20 | $297,220.89 |
| 11 | $1,520.06 | $376.15 | $1,896.20 | $296,934.63 |
| 12 | $1,520.06 | $376.15 | $1,896.20 | $296,646.82 |
| 13 | $1,703.37 | $192.84 | $1,896.20 | $296,357.46 |
| 14 | $1,703.37 | $192.84 | $1,896.20 | $296,066.52 |
| 15 | $1,703.37 | $192.84 | $1,896.20 | $295,774.01 |
| 16 | $1,703.37 | $192.84 | $1,896.20 | $295,479.92 |
| 17 | $1,703.37 | $192.84 | $1,896.20 | $295,184.23 |
| 18 | $1,703.37 | $192.84 | $1,896.20 | $294,886.94 |
| 19 | $1,703.37 | $192.84 | $1,896.20 | $294,588.04 |
| 20 | $1,703.37 | $192.84 | $1,896.20 | $294,287.52 |
| 21 | $1,703.37 | $192.84 | $1,896.20 | $293,985.37 |
| 22 | $1,703.37 | $192.84 | $1,896.20 | $293,681.59 |
| 23 | $1,703.37 | $192.84 | $1,896.20 | $293,376.16 |
| 24 | $1,703.37 | $192.84 | $1,896.20 | $293,069.08 |
| 25 | $1,896.20 | $0.00 | $1,896.20 | $292,760.33 |
| 26 | $1,896.20 | $0.00 | $1,896.20 | $292,449.91 |
| 27 | $1,896.20 | $0.00 | $1,896.20 | $292,137.81 |
| 28 | $1,896.20 | $0.00 | $1,896.20 | $291,824.02 |
| 29 | $1,896.20 | $0.00 | $1,896.20 | $291,508.53 |
| 30 | $1,896.20 | $0.00 | $1,896.20 | $291,191.33 |
| 31 | $1,896.20 | $0.00 | $1,896.20 | $290,872.41 |
| 32 | $1,896.20 | $0.00 | $1,896.20 | $290,551.77 |
| 33 | $1,896.20 | $0.00 | $1,896.20 | $290,229.39 |
| 34 | $1,896.20 | $0.00 | $1,896.20 | $289,905.26 |
| 35 | $1,896.20 | $0.00 | $1,896.20 | $289,579.37 |
| 36 | $1,896.20 | $0.00 | $1,896.20 | $289,251.73 |
Without subsidy, the borrower supplies $1,896.20 monthly; balances match.
Over 36 months, the borrower contributes $61,435.52 in the illustrated plan, while the fund supplies $6,827.82. Without it, the borrower supplies all $68,263.35. Interest charged over those months is $57,515.07 in either calculation. No extra principal reduction results.
Test year three without a refinance
For the hypothetical $1,800 principal-and-interest capacity, year one leaves $279.94, year two leaves $96.63 and year three is short $96.20 each month. The contribution increases about $183.31 at month 13 and $192.84 at month 25. Compared with year one, the month-25 burden is about $376.15 higher.
Replace $1,800 with the amount your household can sustain after its other commitments and ownership costs. A planned raise or refinance is not cash available today. If the final payment does not fit without either event, consider a smaller purchase or a different timing plan rather than treating two manageable years as proof of long-term affordability.
Ask what happens to unused money
At payoff, follow the agreement and Fannie Mae’s rules; refunds are not guaranteed.
In this model, immediately after payment 12 the fund still contains $2,314.04. If you are comparing a proposed payoff at that point, identify how that amount will be handled before treating it as cash for your next transaction. This illustration does not calculate a real payoff quote or establish who receives any remainder.
For a separate comparison, see the permanent mortgage-points calculation. Here, the decision is whether the later payment works and whether the offered early contribution is valuable after reviewing the complete purchase terms. U.S. educational information, checked October 19, 2026; no individualized lending advice.

Mortgage Charge Questions: Choose the Record That Answers Them
Match a questionable mortgage charge to account detail, service records or adjustments with a worked property-inspection example and a two-part index.

Partial Mortgage Payment: Track Money Held in Suspense
Follow a fictional $1,100 and $700 mortgage payment trail, compare dated records, and build a precise question about an unexplained entry.

Minnesota Contract for Deed: Check the Seller, Title and Balloon
Before signing a Minnesota contract for deed, organize seller, disclosure and title evidence, then test a fictional balloon-payment ledger.