2025 IRA Gifts: Compare Payment Routes
For 2025 records, IRS Publication 590-B describes a qualified charitable distribution (QCD) as a payment directly from an IRA trustee to an eligible charity.
Estimated reading time: 1 minute
For 2025 records, IRS Publication 590-B describes a qualified charitable distribution (QCD) as a payment directly from an IRA trustee to an eligible charity. Age and other requirements also apply.
Compare completed electronic payments
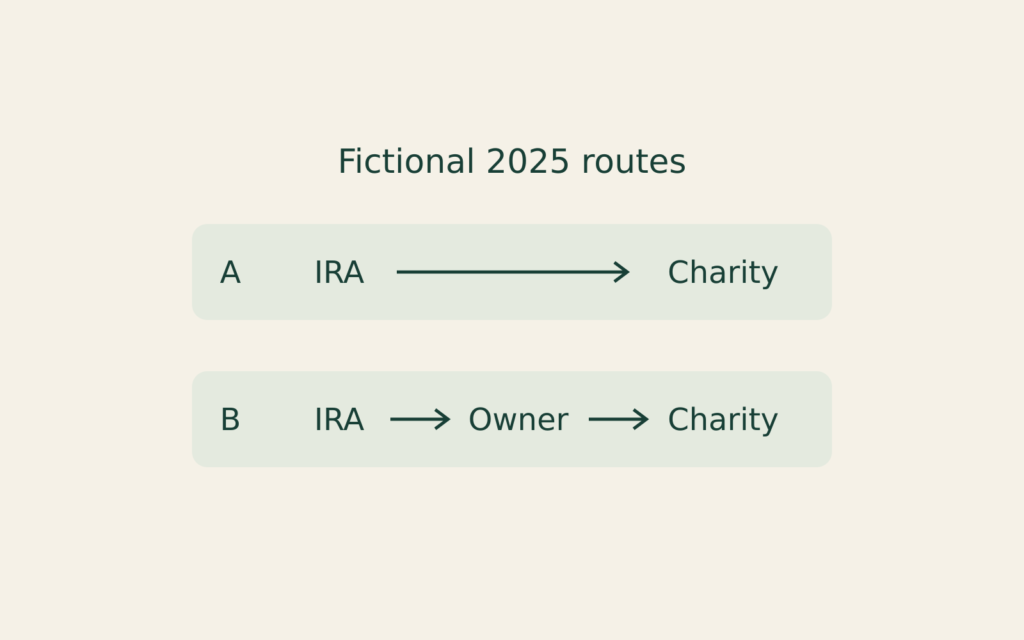
Fictional records concern an original-owner traditional IRA (not an ongoing SEP or SIMPLE IRA), an owner aged 75 and an eligible charity. Compare alternative histories, not instructions to withdraw:
- A: The IRA trustee transfers $1,000 directly to the charity.
- B: The IRA pays $1,000 into the owner’s personal account; the owner then pays $1,000 to the charity.
The charity receives $1,000 either way. A satisfies the direct-payment element; B’s later donation does not turn its earlier payment to the owner into a direct trustee-to-charity payment.
This isolates routing, not final QCD eligibility or an exclusion amount. Preserve the trustee’s transaction record and the charity’s acknowledgment. Annual limits, otherwise-taxable amounts and other restrictions still require review; this example calculates neither tax savings nor a charitable deduction.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.