Stock Basis After Nondividend Distributions
A nondividend distribution can exceed the investment basis still available to recover.
Estimated reading time: 1 minute
A nondividend distribution can exceed the investment basis still available to recover.
Reconcile the receipt and remaining basis
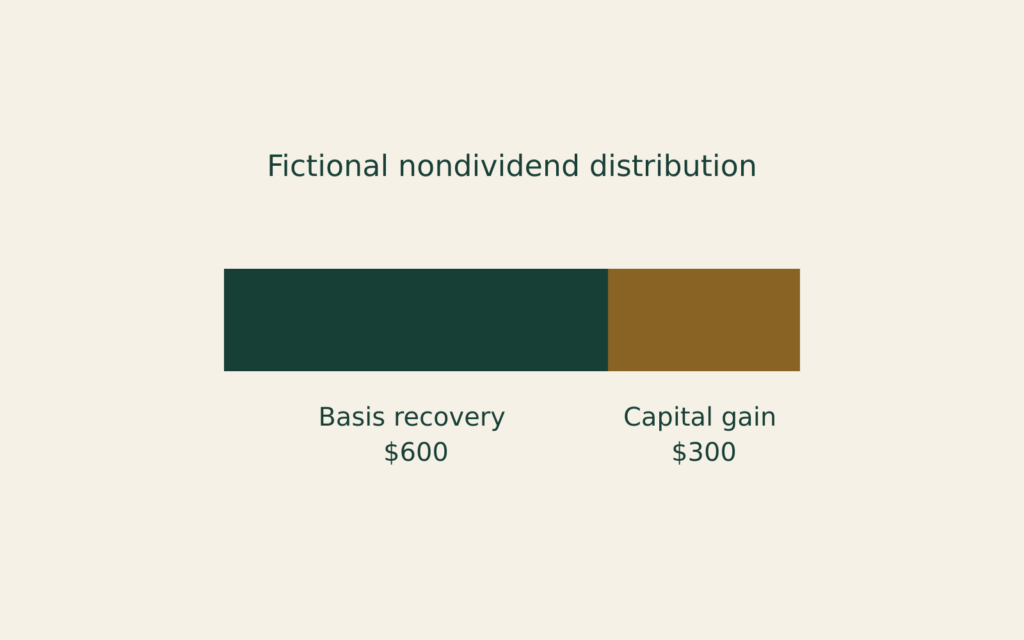
Assume an individual holds one purchased lot of ordinary investment stock in a taxable account. Records establish its adjusted basis immediately before a 2025 payment as $600, after all earlier adjustments. The final issuer statement correctly identifies the entire $900 payment as a nondividend distribution. There is no liquidation, redemption, mixed distribution, sale or other basis adjustment.
IRS Publication 550 (2025) reduces stock basis for a nondividend distribution and treats the amount beyond zero basis as capital gain.
Here, $600 recovers the remaining basis without being taxed. The other $300 is capital gain: $900 minus $600. Remaining basis is zero, not negative $300. The owner still received $900 cash.
The distribution label alone does not establish how much basis remains. This example determines neither short- versus long-term treatment, net capital gain nor tax owed, and does not classify an actual issuer payment.
Rent-to-Own: Remaining Purchase Costs
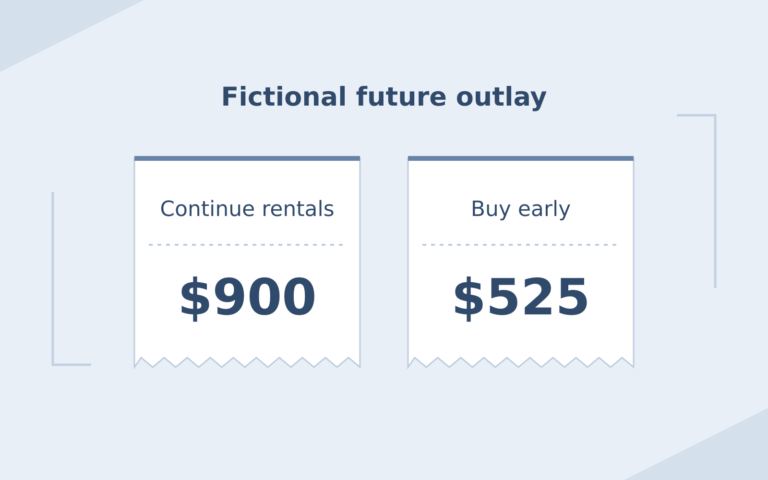
Compare future outlay and available cash.
Lease Payment Components
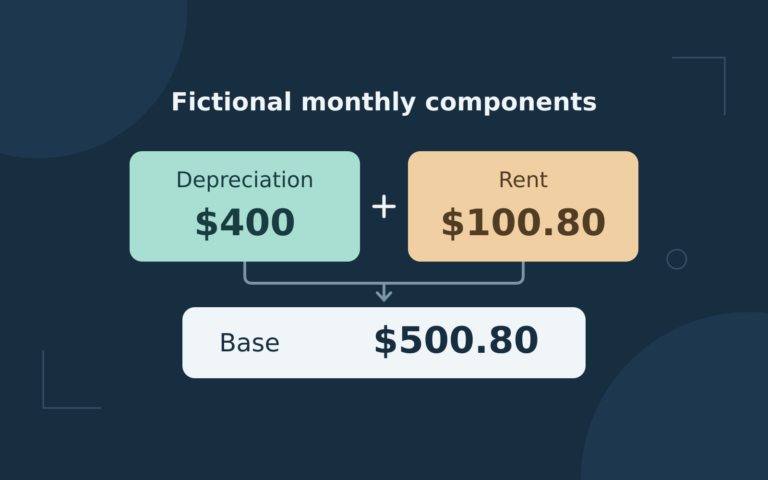
Separate depreciation and rent calculations.
Unused Credit Fees and Utilization
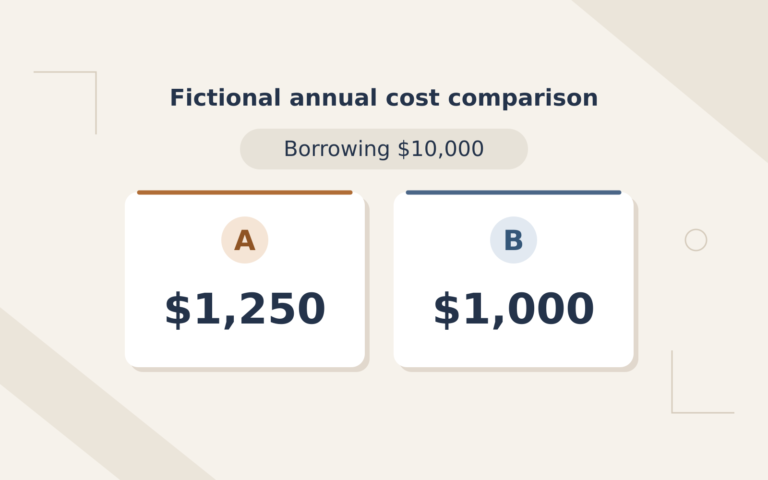
Compare drawn and undrawn costs.