Stock Split and Partial-Sale Basis
A split changes the shares sharing a lot’s basis, not the lot’s total basis.
Estimated reading time: 1 minute
A split changes the shares sharing a lot’s basis, not the lot’s total basis.
Follow one lot through a partial sale
Assume an individual holds one purchased lot of 100 ordinary common shares in a taxable account, with a documented $10,000 adjusted basis. A verified ordinary two-for-one stock split produces 200 uniform, identical shares. There is no fractional-share cash, reorganization, different-class stock, other transaction or basis adjustment.
The IRS stock-split guidance allocates the old basis across the old and new shares. The lot still has $10,000 basis; each share now has $50 basis: $10,000 divided by 200.
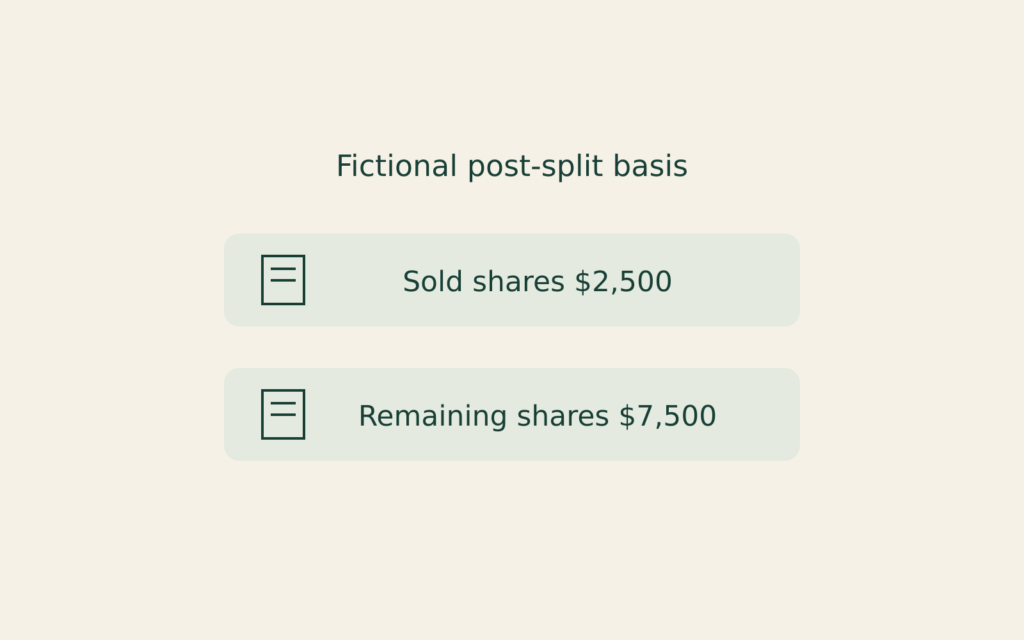
A later sale of 50 of these shares uses $2,500 basis: 50 times $50. The remaining 150 shares retain $7,500 basis. Together, $2,500 plus $7,500 reconciles to $10,000—not $20,000.
Do not use the entire lot’s basis for that partial sale. This example does not validate a corporate action, calculate gain or tax, or select among different lots.
Mid-Quarter Depreciation Across Purchases
Check the entire acquisition pool.
Alternative Minimum Tax Reconciliation
Separate tentative and additional tax.
Self-Employed Health Insurance Limits
Check coverage eligibility before enrollment.