Roth Withdrawals: Track Regular Contributions
Track unrecovered regular Roth IRA contributions across accounts and prior withdrawals. Follow a 2025 example showing when a withdrawal reaches earnings.
Estimated reading time: 1 minute
A nonqualified Roth IRA withdrawal is not automatically all earnings.
IRS Publication 590-B (2025) applies ordering rules across an owner’s Roth IRAs: regular contributions come first. Their return is excluded from gross income.
Reconcile the contribution history
Assume an original owner, alive throughout 2025, first established ordinary Roth IRAs in 2024 and is now 60. Verified valid regular contributions totaled $5,000; prior distributions already recovered $2,000. There are no contributions for 2025, conversions, rollovers, recharacterizations, corrective distributions or special transactions; exclude SEP, SIMPLE and employer-plan accounts.
The owner’s only 2025 distribution is an ordinary $2,000 cash withdrawal. The five-year qualification period has not elapsed.
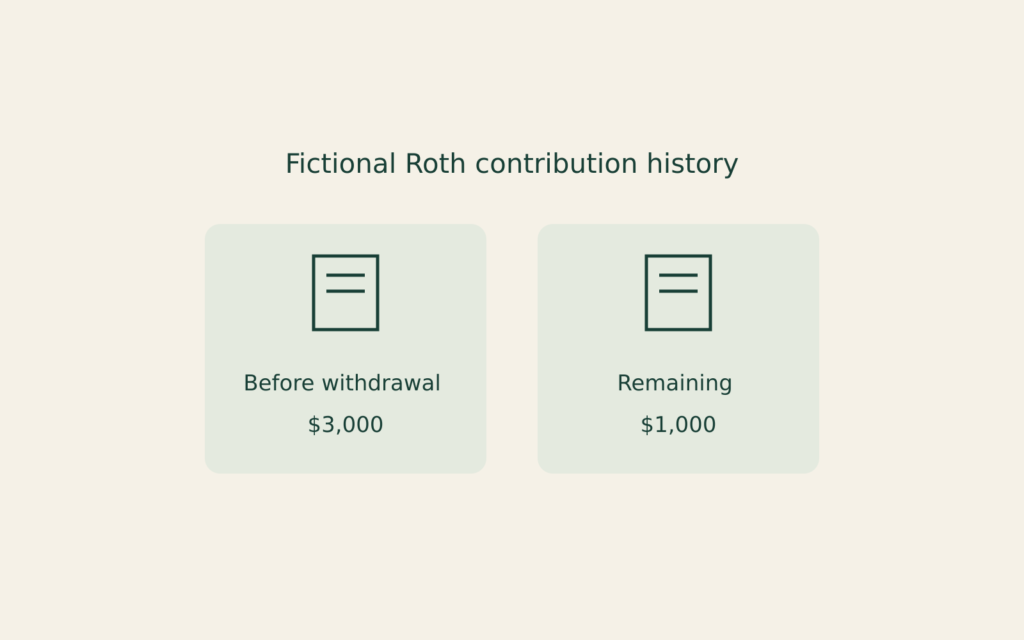
- Unrecovered regular contributions: $5,000 − $2,000 = $3,000.
- Current withdrawal allocated to contributions: $2,000.
- Remaining unrecovered contributions: $3,000 − $2,000 = $1,000.
No earnings are reached in this example. The remaining $1,000 is a contribution-history amount, not the account’s market value. Keep prior recoveries with all Roth IRA records; this does not validate a tax return or recommend a withdrawal.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.