Installment Sale: Recapture First
Reconcile deferred gain.
Estimated reading time: 1 minute
Installment payments do not postpone depreciation recapture.
A fictional U.S. nondealer sole proprietor bought a freestanding machine for $10,000 in 2022, using it exclusively in business. Verified allowed-and-allowable depreciation is $6,000. It is separately accounted, not inventory.
In 2025, an unrelated buyer pays $3,000 down and gives an ordinary $12,000 note due in 2026 with adequate stated interest. No debts, expenses, other adjustments or transactions apply; the seller uses the installment method.
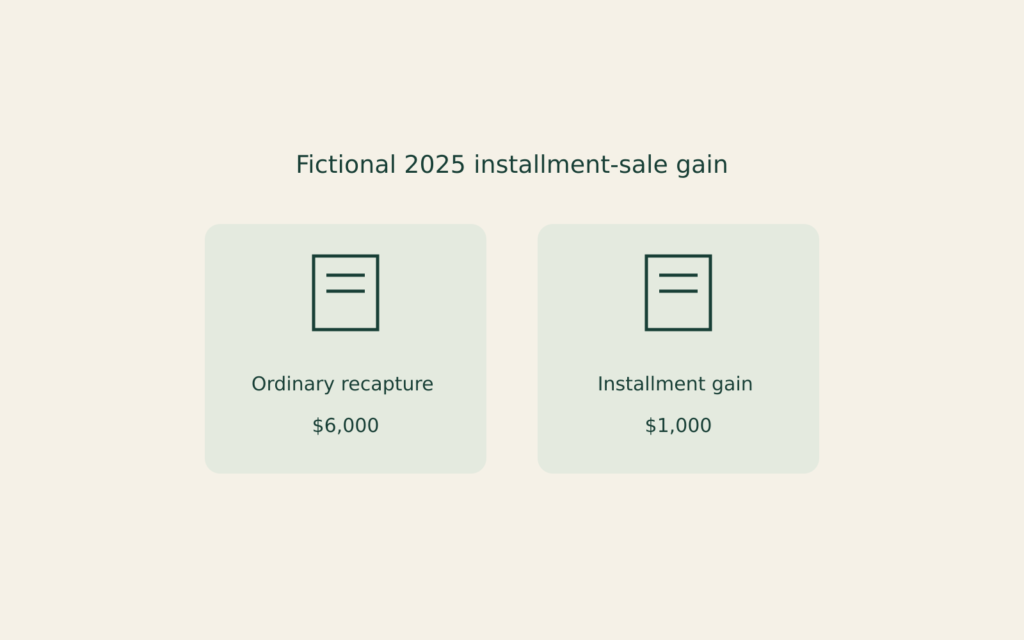
Basis is $4,000; total gain is $15,000−$4,000=$11,000. Ordinary recapture is the smaller of depreciation and gain: $6,000.
Publication 537 requires all $6,000 in 2025, despite only $3,000 cash. Installment-purpose basis includes recapture: $4,000+$6,000=$10,000. Remaining gross profit is $5,000; divided by $15,000 contract price, the fraction is one-third.
The down payment adds $1,000 installment gain; total 2025 recognized gain is $7,000. $2,000 is not taxed again. Remaining $12,000 principal contains $4,000 deferred gain and $8,000 not taxed again—not another $6,000 recapture. Residual section 1231 gain remains subject to netting/lookback; interest and final tax are separate.
Mid-Quarter Depreciation Across Purchases
Check the entire acquisition pool.
Alternative Minimum Tax Reconciliation
Separate tentative and additional tax.
Self-Employed Health Insurance Limits
Check coverage eligibility before enrollment.