Mid-Quarter Depreciation Across Purchases
Check the entire acquisition pool.
Estimated reading time: 1 minute
A late-year purchase can change depreciation on equipment already placed in service.
Fictional 2025 calendar-year case: a U.S. sole proprietor buys and immediately places two new, separately accounted desktop computers in service: $4,000 on February 1 and $6,000 on November 1. Both serve only ordinary business recordkeeping, with no personal use. These are the year’s only property acquisitions; neither is disposed of.
No section 179 deduction, credits or other basis adjustments apply. The owner validly elects out of bonus depreciation for the entire five-year class and uses ordinary GDS 200% declining balance.
Publication 946’s mid-quarter test compares last-three-month depreciable basis with the full-year pool: $6,000÷($4,000+$6,000)=60%, exceeding 40%. Both computers therefore use the mid-quarter convention.
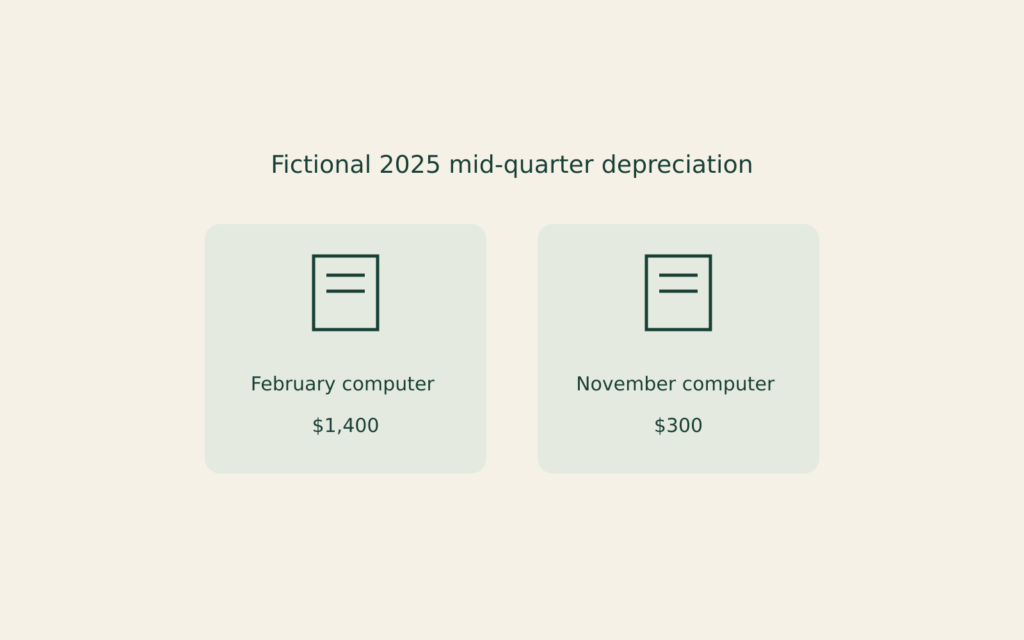
Five-year Tables A-2 and A-5 give first-year rates of 35% and 5%: $1,400 for February’s computer and $300 for November’s, totaling $1,700.
Applying Table A-1’s 20% half-year rate to both would incorrectly yield $2,000. Even the earlier computer’s deduction is $1,400, not $800. These deductions are not tax savings.
Alternative Minimum Tax Reconciliation
Separate tentative and additional tax.
Self-Employed Health Insurance Limits
Check coverage eligibility before enrollment.
Wages and Self-Employment Tax Bases
Allocate two different tax bases.