Roth Conversion and Account Clocks
Separate five-year tests.
Estimated reading time: 1 minute
IRS Publication 590-B (2025) distinguishes a Roth IRA’s qualification clock from each conversion’s five-year additional-tax clock.
Conversion record
Fictional calendar-year taxpayer first funded an ordinary Roth IRA for 2010. At age 45 in 2025, their records show all regular contributions previously withdrawn and one valid, untouched $12,000 conversion made in 2023, entirely included in 2023 income. There are no other conversions, rollovers or special transactions.
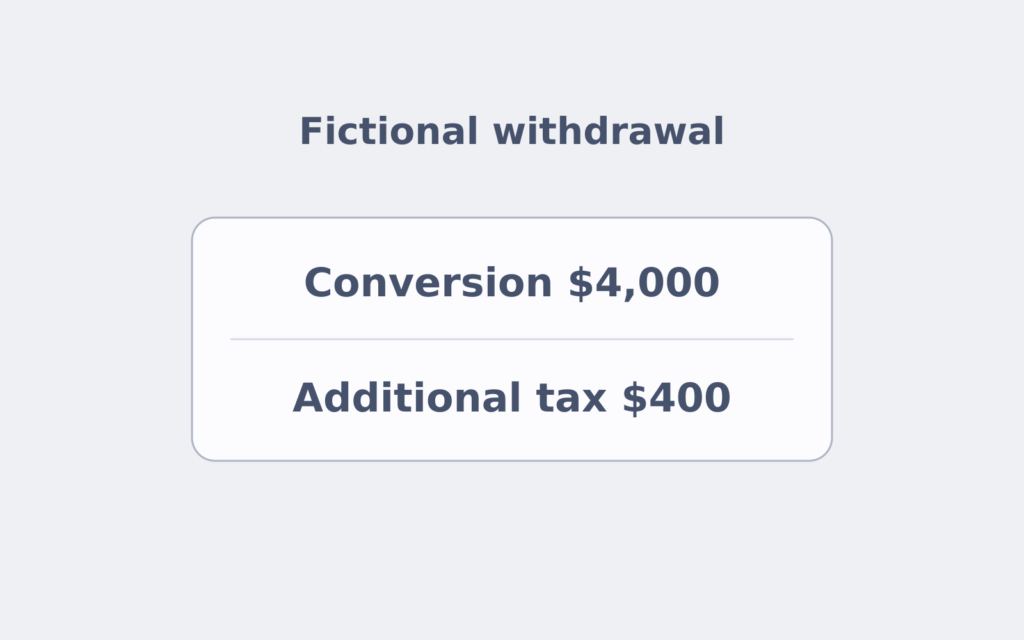
Their only 2025 withdrawal is $4,000. No additional-tax exception applies. Ordering rules allocate all $4,000 to the taxable 2023 conversion; no earnings are reached.
The conversion’s period runs January 1, 2023 through December 31, 2027. The 2025 withdrawal falls inside it: $4,000 × 10% = $400 additional tax.
The $4,000 is not included in ordinary income again. Remaining conversion principal is $12,000 − $4,000 = $8,000.
Separate clocks
The older account does not erase the conversion clock. Account age alone also does not establish a qualified distribution. Preserve contribution recoveries and conversion-year tax records. No transaction recommendation or full tax calculation.
ABLE Distributions Across Month-End
Separate retained purposes.