Charitable Gifts: Interacting Limits
Reconcile cash and stock gifts.
Estimated reading time: 1 minute
Charitable percentage limits interact; separate maximum percentages cannot simply be added.
Consider a fictional single U.S. taxpayer itemizing for 2025 with $100,000 adjusted gross income. Their only gifts were $40,000 cash and ordinary publicly traded investment stock with $40,000 fair market value at contribution, with $10,000 basis, held for three years. Both were completed outright gifts to a verified qualifying public charity in the IRS’s 50%-limit category. All valuation, acknowledgment and substantiation requirements are satisfied; no benefits, prior carryovers, special contributions or capital-gain-property election apply.
Under IRS Publication 526, the cash gift is considered first: $40,000 fits within the $60,000 cash ceiling. The stock deduction is the smaller of $30,000 or $50,000 minus $40,000: $10,000.
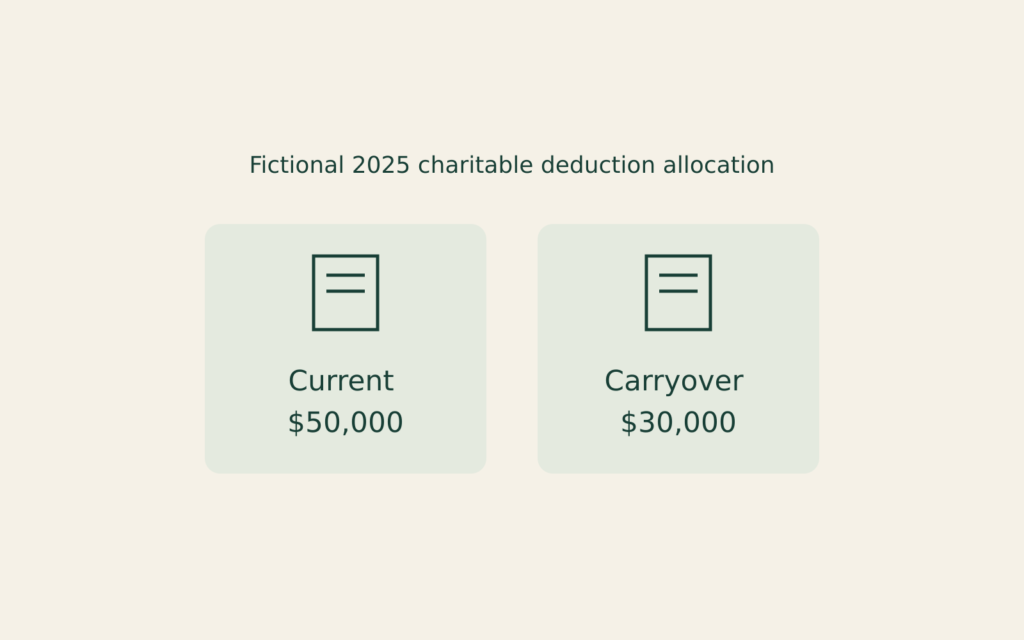
The current deduction is therefore $50,000, not $70,000. The remaining $30,000 is a capital-gain-property contribution carryover, generally subject to applicable limits over the next five years—not an automatic next-year deduction or tax refund. Match each gift’s category to its deduction and carryover records.
Insurance Gain and Replacement Basis
Reconcile replacement spending and postponed gain.
Foreign Income: Two Periods
Reconcile qualification and annual proration.
Earned Income Credit: Two Lookups
Compare earned income and AGI.