Create a Recordkeeping Routine That Makes Tax Season Easier
Last Update: 11 Sept, 2026.
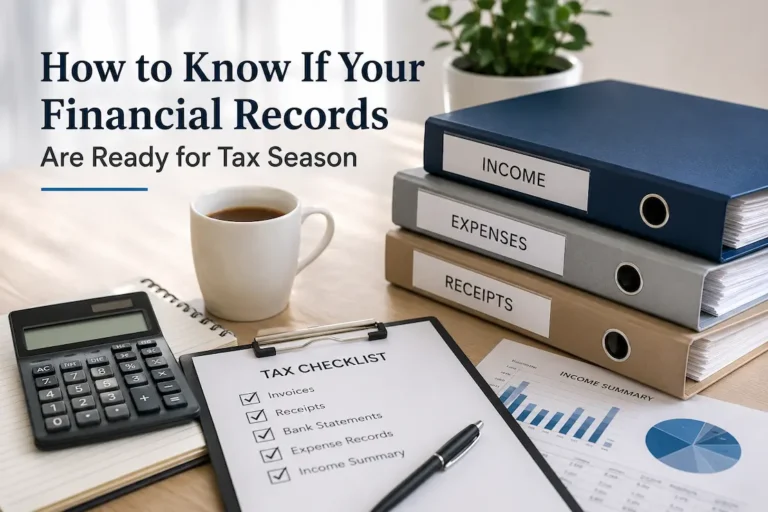
Tax preparation becomes difficult when the records behind the return have been scattered across email, bank statements, payment apps, paper receipts, downloaded invoices, and memory. For a self-employed person, the problem is usually not that information does not exist. It is that the information was never organized in a way that makes sense when tax time arrives. The IRS says good records help businesses identify income, track deductible expenses, prepare tax returns, and support the items reported on those returns.
A useful recordkeeping system does not need to look like corporate accounting software. The IRS generally does not require a particular recordkeeping format as long as the system clearly shows business income and expenses, although specific businesses and transactions can have additional requirements. The better goal for a freelancer or small business owner is to create a routine that is simple enough to maintain during busy weeks and detailed enough to answer questions months later.
Think of Records as a Running Explanation
A good record is more than a number. It should help explain where money came from, what it was spent on, when the transaction happened, and why it belonged in the business records. That context can be easy to remember when a purchase is made but surprisingly difficult to reconstruct many months later. Recording the transaction while the details are still fresh reduces the amount of detective work required at filing time.
For example, a $240 charge on a business card may be obvious to you today. Six months later, the same charge may simply look like a vague merchant name on a statement. If the original invoice or receipt has been saved and the transaction has been categorized, the purpose is much easier to establish. This is one reason the IRS recommends keeping supporting documents such as invoices, receipts, deposit slips, paid bills, and other records connected to business transactions.
Start With Four Separate Streams of Information
Instead of trying to create an elaborate bookkeeping system immediately, begin by identifying the information that has to remain visible throughout the year. For many self-employed businesses, that means tracking income, ordinary business expenses, assets or larger purchases, and tax-related payments or documents. The exact records needed depend on the type of business, but separating these streams prevents unrelated transactions from becoming one large pile of receipts.
Income Needs Its Own Trail
Record income when it enters the business records according to the accounting method that applies to the business, and keep enough information to identify its source. Invoices, payment-platform reports, bank deposits, Forms 1099, and other supporting documents can help establish where business receipts came from. The IRS also notes that income generally must be reported even when a payer does not issue a Form 1099.
This becomes particularly important when clients use different payment methods. A freelancer might receive one payment through a bank transfer, another through a payment platform, and another by check. Looking at only one account can therefore produce an incomplete picture of business income. The recordkeeping system should bring those sources together rather than assuming that the annual tax forms received from clients will automatically provide the complete answer.
Give Every Transaction a Home
A recordkeeping system becomes easier when every transaction has a predictable destination. That could be accounting software, a spreadsheet, a bookkeeping application, or another organized electronic system. The technology matters less than consistency. The IRS states that electronic systems are subject to the same basic recordkeeping principles as paper records and should provide a complete and accurate record that remains accessible.
The mistake is to create several competing systems without deciding which one is the main record. For example, a freelancer might track expenses in a spreadsheet, keep some receipts in email, save others in a phone folder, and write a few transactions in a notebook. Each individual method may work, but together they create uncertainty. Choose one primary system and use supporting folders or documents to preserve the evidence behind it.
Make the Filing Structure Boring
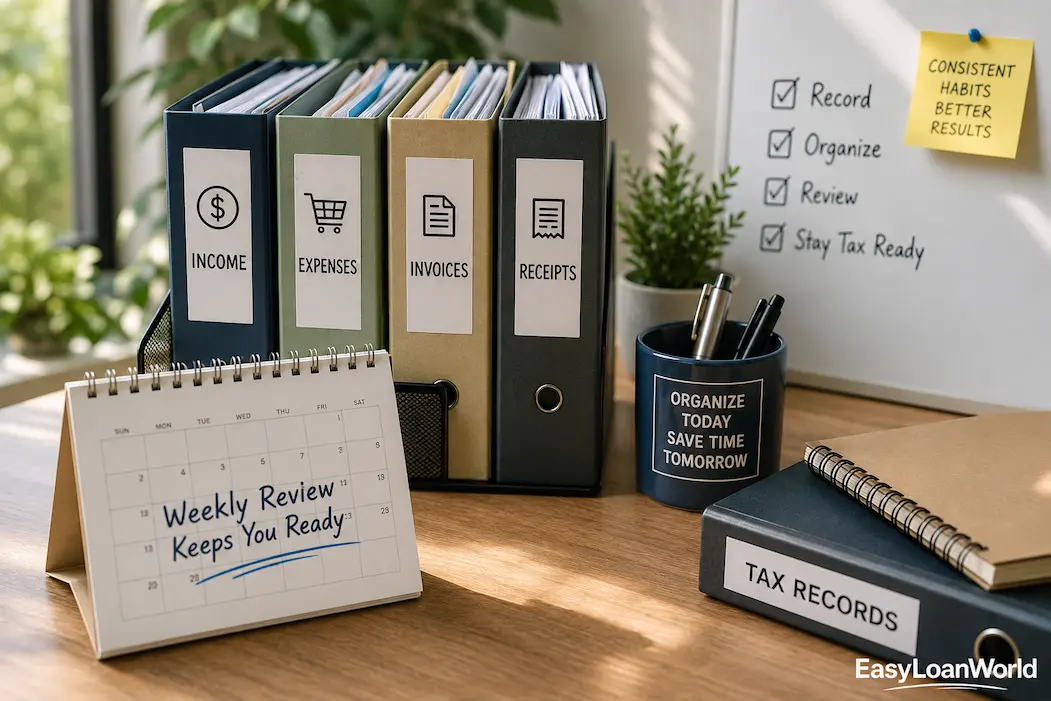
Boring is useful when it comes to records. A simple folder structure such as 2026 → Income → Expenses → Assets → Tax Documents can be more valuable than a complicated filing system that requires constant maintenance. Within the expense section, categories can be separated further if that makes the business easier to understand, but there is no need to create dozens of folders merely to make the system look sophisticated.
The same principle applies to digital files. Give receipts and invoices recognizable names rather than leaving everything as files called “IMG_4837” or “receipt.pdf.” A name containing the date, vendor, and general purpose can make a later search dramatically easier. The objective is not beautiful organization. It is being able to find supporting information without reconstructing the transaction from scratch.
Build a Small Routine Around the Week
Recordkeeping usually becomes difficult when it is treated as a large monthly or annual project. A small routine can be easier to maintain. The IRS says it is generally best to record business transactions daily, although the appropriate system depends on the business.
That does not mean a freelancer must spend an hour every evening doing bookkeeping. For a small operation, a few minutes may be enough to capture a new expense, save the receipt, categorize a payment, or identify an invoice that has been paid. The important part is preventing transactions from accumulating into an unexplained backlog.
The Five-Minute Capture Rule
When a business expense occurs, capture the supporting document immediately or as close to the transaction as practical. If a receipt arrives by email, save it. If it is printed, photograph or scan it. If a payment is made online, preserve the confirmation. If a transaction needs explanation, add that explanation while the reason is still obvious.
This small habit changes the nature of tax preparation. Instead of asking, “What did I spend money on last March?” you are reviewing information that was already captured during March. The difference may seem minor during an ordinary week, but it becomes significant after hundreds of transactions have accumulated.
Review the Records Before They Become Old
Capturing transactions is only half of the routine. A business can have every bank statement and receipt saved and still have inaccurate records if transactions are duplicated, categorized incorrectly, or never reconciled. A periodic review provides an opportunity to compare the bookkeeping system with actual bank and payment-account activity.
Reconcile the Money, Not Just the Receipts
Suppose the records show $6,200 of business income for a month, but the connected bank and payment accounts show deposits totaling $6,850. That difference should have an explanation. It might involve a deposit recorded in another period, a transfer between accounts, a refund, a personal transaction, or an income item that was never entered. The point of reconciliation is not simply to make two numbers match; it is to understand why they differ.
The same principle applies to expenses. If a business card statement shows a charge that does not appear in the expense records, investigate it. If the same receipt appears twice, remove the duplicate. If a personal purchase was accidentally charged to the business account, identify it rather than quietly leaving it categorized as a business expense.
Keep Business and Personal Records From Blending Together
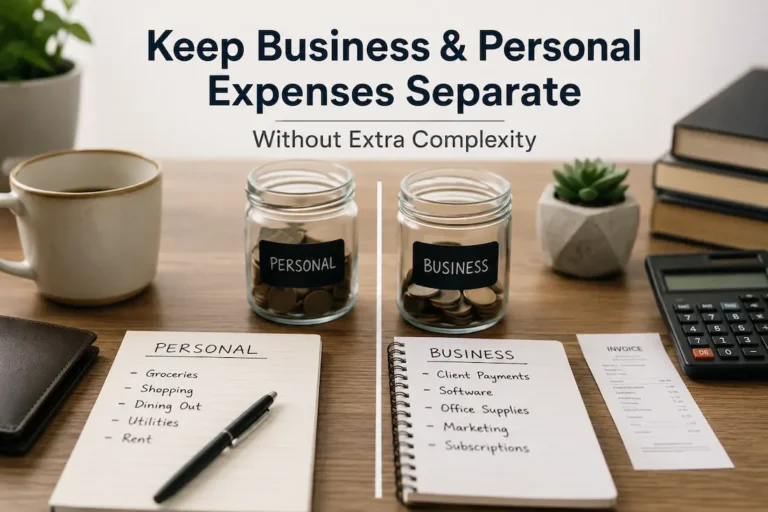
Separate business and personal finances make recordkeeping considerably easier. The IRS Publication 583 discusses maintaining a business checking account separately from a personal checking account as part of a practical recordkeeping system.
This does not mean every self-employed person needs a complicated banking structure. It means the fewer personal transactions mixed into business records, the less time is required to determine what actually belongs to the business. When a mixed transaction does happen, identify it promptly and record only the appropriate business portion where the tax rules permit a business deduction.
Do Not Let the Bank Statement Become the Bookkeeping System
A bank statement is evidence of transactions, not necessarily a complete explanation of them. A merchant name may not tell you what was purchased, and a deposit may not clearly identify which client paid it. Your bookkeeping records should add the context that a raw statement cannot provide.
This is especially important for purchases that could have both business and personal elements. A computer, phone, vehicle, home expense, or subscription may require more analysis than simply labeling the transaction “business.” The supporting records should make it possible to understand how the expense relates to the business and, where applicable, how business and personal use were distinguished.
Treat Larger Purchases Differently
Ordinary recurring expenses are usually easier to recognize than significant equipment or property purchases. A large purchase may have consequences that extend beyond the month in which the money left the bank account. Depending on the property and applicable tax rules, depreciation, Section 179, business-use percentages, basis, or other rules may affect the eventual tax treatment.
The recordkeeping system should therefore preserve more than the receipt. The IRS notes that records for business assets may need to establish information such as when and how the asset was acquired, its cost, improvements, depreciation or Section 179 deductions, business use, and eventual disposition.
Create an Asset Record at the Time of Purchase
If a freelancer buys a $2,400 computer for the business, do not simply save the receipt under “October expenses” and forget about it. Record the purchase date, amount, description, and relevant business-use information in a way that can be found later. If the item is subject to depreciation or another specific tax treatment, the supporting information will already be available when the return is prepared.
This becomes even more useful when equipment is sold, replaced, transferred, or used differently later. An asset record creates a history rather than forcing the taxpayer to reconstruct the original purchase years after the transaction happened.
Give Receipts a Purpose
A receipt proves that a transaction occurred, but it may not explain the business reason behind it. For some expenses, that distinction matters. If the merchant description is vague, an additional note can provide useful context about what the expense was for and how it related to the business.
For example, “$185 — Office Depot” tells you much less than “$185 — replacement printer for client-document production.” The second note does not automatically make the expense deductible, but it preserves information that can help explain the transaction later. Good records support a tax position; they do not create one where the underlying tax rules do not allow it.
Do Not Save Everything Without Classifying Anything
More documents do not necessarily mean better records. A folder containing thousands of unsorted receipts may technically preserve information while still being difficult to use. The useful system connects each document to a transaction and gives the transaction enough context to be understood.
The IRS says supporting documents should be kept in an orderly fashion and gives examples such as organizing them by year and type of income or expense. That is a useful principle for digital records as well: preserve the evidence, but make the evidence searchable and connected to the bookkeeping entry.
Set One Monthly Cleanup Point
A monthly review can catch small problems before they become year-end problems. Pick a consistent point near the end of each month and review the business accounts, payment platforms, invoices, receipts, and expense records. The purpose is not to prepare the tax return. It is to make sure the year’s records are steadily becoming more complete.
During the review, look for missing income, uncategorized transactions, duplicate entries, unexplained transfers, missing receipts, unusually large expenses, and purchases that may need separate asset treatment. Also check invoices that remain unpaid so that the business’s cash-flow picture is not confused with its bookkeeping records.
Keep a Short List of Questions
Some transactions will not be obvious. Instead of making a questionable classification immediately just to clear the bookkeeping screen, mark it for review. A short list might include “Was this partly personal?”, “Is this an asset?”, “Which client paid this?”, or “What was this subscription used for?”
That list can then be resolved during the monthly review or discussed with a tax professional. This is better than relying on memory at filing time, particularly when the transaction is several months old. A recordkeeping routine should make uncertainty visible rather than hiding it.
Use the Slow Months to Catch Up
A quiet period in the business can be a useful time to repair the recordkeeping system. Review older bank statements, organize missing receipts, reconcile payment accounts, and identify transactions that have been sitting in an uncategorized state. The goal is to bring the records back to a point where current activity can once again be maintained routinely.
This is also a good opportunity to improve the system itself. If receipts constantly disappear in email, create a dedicated folder. If payment-platform income is difficult to reconcile, change how those transactions are recorded. If a spreadsheet has become too difficult to maintain, consider whether accounting software or professional bookkeeping would reduce the workload.
Fix the Process Instead of Repeating the Cleanup
A yearly cleanup may solve the immediate problem, but it does not solve why the problem happened. If the same missing documents appear every tax season, the recordkeeping process needs to change. Perhaps receipts should be captured at the time of purchase, bank accounts should be reconciled monthly, or one payment platform needs its own reconciliation procedure.
The most effective routine is not necessarily the most detailed one. It is the one that fits the way the business actually operates. A freelancer who rarely has more than a few dozen transactions a month may need very different tools from an online seller processing hundreds of payments.
Know How Long to Keep the Records
Record retention should not be based on a blanket rule such as “throw everything away after three years.” The IRS explains that the appropriate retention period depends on the document, transaction, deduction, or event involved. Generally, records supporting an item of income, deduction, or credit should be kept until the relevant period of limitations expires.
Some records need to be retained longer than ordinary supporting documents. Asset records, for example, may need to be kept for as long as they are relevant to determining the property’s tax basis and the tax consequences of its eventual disposition. Employment tax records have their own retention requirements as well.
Keep the Filed Return With Its Supporting Records
Do not treat the final tax return as the end of the recordkeeping process. Keep a copy of the filed return together with the records used to prepare it. The IRS notes that copies of filed returns can help with future returns and amended-return calculations.
A useful archive therefore contains both the return and the underlying records that explain it. If a question arises later, you should be able to move from the tax return to the relevant bookkeeping records and then to the supporting documents without starting the search from zero.
Choose Tools Based on the Business, Not the Trend
A spreadsheet can be perfectly adequate for a simple freelance operation. Accounting software may make more sense when transactions become frequent, multiple accounts are involved, invoices need regular tracking, or financial statements are useful for decision-making. The IRS recognizes both paper and electronic systems as potential recordkeeping methods as long as the records meet the applicable requirements.
The wrong tool can actually make recordkeeping worse. If software requires more maintenance than the business owner can realistically provide, transactions may remain incomplete. Conversely, a simple spreadsheet may become difficult to control when transaction volume grows. The right question is not which tool looks most professional. It is whether the system consistently captures accurate information and supporting evidence.
A Recordkeeping Routine That Can Actually Survive a Busy Year
A workable routine can be surprisingly small. Capture income and expenses as they occur, save the supporting documents, reconcile the business accounts regularly, flag unusual transactions, and perform a more complete monthly review. Larger purchases should receive additional attention, and uncertain tax treatment should be identified rather than guessed.
The IRS does not require every small business to use an elaborate bookkeeping structure. What matters is that the chosen system clearly shows the business’s income and expenses and supports the information reported on the tax return. A simple system used consistently is usually more valuable than an impressive system that gets abandoned after a few weeks.
Final Takeaway
Tax-season preparation becomes much easier when recordkeeping is treated as an ongoing business habit instead of an annual rescue project. Capture transactions while they are fresh, preserve the documents that support them, keep business and personal activity distinguishable, reconcile accounts regularly, and give unusual or significant purchases enough attention to explain them later. Good records help with more than filing a return; they also give a self-employed person a clearer view of how the business is actually performing.
The best routine is the one you can maintain when business is both busy and slow. If the system still works during your busiest month, there should be far less to reconstruct when tax season arrives.
Do I need accounting software to keep good tax records?
No. The IRS generally allows businesses to choose a recordkeeping system suited to their operations, provided it clearly shows income and expenses and satisfies applicable requirements. That system can be paper-based or electronic.
What documents should a freelancer keep?
Depending on the business, useful supporting documents can include invoices, receipts, paid bills, bank records, deposit slips, payment-platform records, Forms 1099, and documentation for business assets. The records should support the income and expenses reported on the tax return.
How often should I update my business records?
There is no single schedule that fits every business, but recording transactions promptly is preferable to allowing a large backlog to build. The IRS says it is generally best to record business transactions daily, while recognizing that recordkeeping systems vary by business.
Should business and personal expenses be kept separate?
Keeping them separate generally makes recordkeeping easier and reduces the amount of work required to identify which transactions belong to the business. The IRS Publication 583 discusses maintaining a separate business checking account as part of a practical recordkeeping system.
How long should I keep my tax records?
It depends on the type of record and the transaction involved. Generally, records supporting income, deductions, and credits should be retained until the applicable period of limitations expires, while certain records may need to be kept longer.
What should I do if I cannot find a receipt?
Do not automatically treat the transaction as deductible simply because it appears on a bank or card statement. Gather whatever legitimate supporting documentation is available, identify what the payment was for, and determine whether the expense can be adequately substantiated under the applicable tax rules. When the tax treatment is uncertain, professional advice may be appropriate.
Official resources: IRS Recordkeeping · IRS Publication 583 — Starting a Business and Keeping Records · IRS — How Long Should I Keep Records?