Down-Payment Savings: Can Waiting Require a Bigger Monthly Deposit?
Compare fictional down-payment savings deadlines when the target changes with the assumed price. Separate exact deposits, cent rounding and fixed-deposit gaps.
Estimated reading time: 8 minutes
Extending a savings deadline gives you more deposit dates. But if the dollar target also rises, the monthly amount needed can increase rather than decrease. A down-payment savings comparison must change both the deadline and the target—not just divide today’s shortfall by more months.
This fictional exercise compares a selected cash share of a hypothetical home price. In one deliberately chosen stress, a four-year plan needs exactly $352.5625 per month, while a five-year plan needs $355.255. That’s a mathematical counterexample, not a home-price forecast or a reason to buy sooner.
Compare alternative plans starting today
Every plan starts with the same inputs:
- A starting comparison price of $300,000.
- A chosen cash-share target of 10% of the price at the selected deadline. This percentage is an exercise choice, not a required or recommended down payment.
- $27,000 already dedicated solely to that target, with none assigned to other goals or reserves.
- One equal deposit at each month-end, with all deposits completed before the deadline check. Four years means 48 deposits; five years means 60.
- Zero savings growth, no withdrawals, no fees, no other funding and no tax effects.
Test three independent fictional price paths: no annual change, 4% annual increases and 10% annual increases, compounded at each anniversary. None is assigned a probability or presented as an expected outcome. The 10% stress is selected to make the reversal visible, not because it describes a particular market.
The chosen 10% cash share and the stress path’s 10% annual price change do different jobs. One determines the portion being saved; the other changes the assumed future price.
This is only an isolated cash-share target. Closing costs, prepaid items, deposits and credits, moving or repair costs, retained reserves, mortgage payments and qualification are outside the model. It doesn’t establish the full cash needed for a purchase.
Update the target before dividing by the deposit count
For a deadline after n whole years and an assumed annual price change g:
- Price at deadline = $300,000 × (1 + g)n.
- Cash-share target = 10% × that price.
- Equal monthly deposit = (target − $27,000) ÷ (12 × n).
Every tested target exceeds the starting fund. Calculations retain the exact amounts; rounding is a separate step.
Under the 10% price-change stress, the four-year price is $439,230 and the selected cash target is $43,923. The remaining $16,923 divided by 48 gives $352.5625. At five years, the assumed price is $483,153 and the cash target is $48,315.30. The remaining $21,315.30 divided by 60 gives $355.255.
| Deadline / deposits | Selected cash target | Unrounded monthly result | Constant whole-cent deposit that meets the target |
|---|---|---|---|
| 1 year / 12 | $33,000.00 | $500 | $500.00 |
| 2 years / 24 | $36,300.00 | $387.50 | $387.50 |
| 3 years / 36 | $39,930.00 | $12,930 ÷ 36 = $359.1666… | $359.17 |
| 4 years / 48 | $43,923.00 | $352.5625 | $352.57 |
| 5 years / 60 | $48,315.30 | $355.255 | $355.26 |
| 6 years / 72 | $53,146.83 | $26,146.83 ÷ 72 = $363.1504166… | $363.16 |
The exact monthly amount falls through year four, then rises at years five and six. Year four has the lowest contribution among these six tested deadlines—not the “best” buying date. This calculation doesn’t compare renting, ownership costs or financing.
Down-payment savings: why the extra year needs more
Compare the increase in the target with what twelve more deposits at the four-year plan’s exact amount would add:
- Target increase: $48,315.30 − $43,923 = $4,392.30.
- Twelve more deposits: 12 × $352.5625 = $4,230.75.
- Unfunded difference: $4,392.30 − $4,230.75 = $161.55.
The additional target exceeds the additional deposits. Keeping $352.5625 for all 60 deposits would therefore leave the five-year target $161.55 short.
To spread that difference across the alternative five-year plan starting today, divide $161.55 by all 60 deposits: $2.6925 more per deposit. Adding that to $352.5625 gives $355.255.
The $2.6925 difference applies to every one of the 60 deposits. It isn’t a catch-up increase to begin after four years have already elapsed. A plan revised after actual deposits have been made would need a new calculation from its then-current balance and remaining dates.
With zero savings growth and the same starting fund, the extension test is: a one-year-later plan needs a larger equal monthly deposit when the target’s increase exceeds twelve deposits at the earlier plan’s exact amount. Here, $4,392.30 exceeds $4,230.75.
Keep display rounding separate from a repeatable deposit
The table’s last column rounds up to a whole cent so that repeating the same amount meets the exact toy target. It isn’t ordinary nearest-cent display rounding.
For example, $352.56 repeated 48 times leaves a $0.12 shortfall. Using $352.57 leaves $0.36 above the four-year target. At five years, $355.26 repeated 60 times leaves $0.30 above the target. Those small differences are rounding effects, not investment earnings.
What if the monthly deposit stays at $350?
Now use a separate fixed-deposit test. Keep the same starting fund and 10% price-change stress, but deposit $350 each month instead of either exact calculated amount.
| Deadline | Ending dedicated fund | Selected cash target | Remaining gap |
|---|---|---|---|
| 4 years | $43,800.00 | $43,923.00 | $123.00 |
| 5 years | $48,000.00 | $48,315.30 | $315.30 |
The fund grows by $4,200: twelve more $350 deposits. The target grows by $4,392.30, so the gap grows by $192.30. More saved dollars don’t close this particular moving gap. Don’t confuse this $4,200 extension with the earlier exact-plan extension of $4,230.75.
Down-payment savings: revise a plan after deposits occurred
The alternative plans above all start today. A later revision is a different question. Suppose the saver actually makes 48 deposits of $350 under the fixed-deposit example. At year four, the dedicated fund is $43,800.
Now assume the saver chooses the five-year deadline under the same fictional 10% price path. The target is $48,315.30, so the remaining gap at that moment is $4,515.30. With 12 month-end deposits left and no growth or other changes, the exact catch-up contribution is $376.275 per month.
A constant whole-cent deposit rounded upward is $376.28. Twelve such deposits add $4,515.36, leaving six cents above the target. This differs from $355.26 because the saver did not follow the alternative five-year plan from its beginning.
Using the five-year plan’s $355.26 for only those final 12 deposits would add $4,263.12. Added to $43,800, that produces $48,063.12, leaving a $252.18 gap. A contribution calculated for 60 deposits can’t simply be imported into a 12-deposit catch-up plan.
Identify which money is still dedicated
The starting $27,000 is assumed to belong entirely to this goal. For an independent sensitivity test, suppose only $24,000 is dedicated, with every other four-year stress input unchanged. The $43,923 target then leaves $19,923 to fund.
Dividing by 48 gives an exact $415.0625 monthly contribution, or $415.07 rounded upward to cents. The $3,000 smaller starting fund increases the exact contribution by $62.50 per month: $3,000 ÷ 48.
This test doesn’t recommend moving money away from another goal or reserve. It shows why a fund used in two plans can’t be counted in full in both. Record which dollars are actually dedicated before comparing the target with deposits.
Down-payment savings: document the revised inputs
For a real planning discussion, retain the dated dedicated balance, remaining deposit dates, chosen target rule and explicit price assumptions. Recalculate when one changes. A previously correct contribution can become outdated without any error in the original arithmetic.
Keep household affordability and the separate purchase costs outside this isolated answer until their own records are assessed. Reaching the selected cash-share target doesn’t establish that the purchase, mortgage or monthly contribution is appropriate.
For a down-payment savings catch-up review, retain the deposits actually completed. The remaining contribution can’t assume missed deposits occurred. Compare the revised down-payment savings result with the household budget separately; solving the equation doesn’t establish that the amount is affordable.
Down-payment savings: change the assumed price path
The reversal is conditional. Under the other two invented paths, the required deposit continues falling across all six tested annual deadlines. The later rows below illustrate the difference; these are separate scenarios, not a forecast range.
| Deadline | 0% annual price change | 4% annual price change | 10% annual price change |
|---|---|---|---|
| 4 years | $62.50 | $168.67 | $352.57 |
| 5 years | $50.00 | $158.33 | $355.26 |
| 6 years | $41.67 | $152.22 | $363.16 |
The useful lesson is to keep the target rule, starting fund and deadline together. Extending time lowers the deposit in some stated paths and raises it in others. Neither result recommends waiting or buying sooner, and a calculated contribution doesn’t establish that it fits a household budget.
For separate worked questions, see monthly homeownership and upfront-cash limits and the closing-cost and cash-to-close worksheet. This isolated savings target doesn’t replace either calculation.
Illustrative stock photo: Silvia Fernanda Marin Giraldo / WordPress Photo Directory (CC0).
Down-Payment Assistance: Is Your Paperwork Enough to Decide?
Use three invented teaching cards to identify missing evidence, resolve version questions and prepare a clearer request for assistance paperwork.
California Supplemental Property Tax: Check the Bill, Payment and Cash
Organize one California supplemental property tax bill, its payment evidence and the cash earmarked for it. A fictional example shows why a funding gap…
Title Insurance Quotes: Compare Policies, Services and Payers
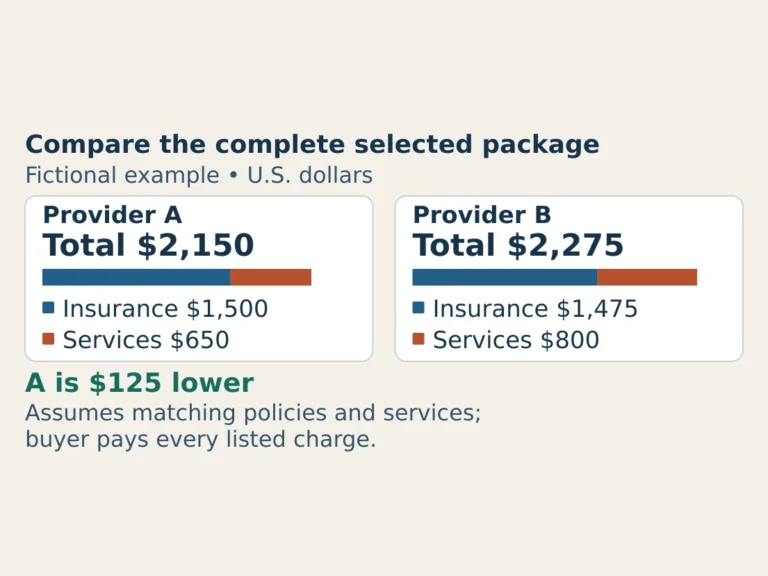
Compare fictional $2,150 and $2,275 title packages using matched coverage, complete service charges and a separate payer worksheet.