Education Bonds: Interest Exclusion
Reconcile tuition and redemption proceeds.
Estimated reading time: 1 minute
Education-bond exclusions compare qualifying expenses with total redemption proceeds, not interest alone.
Consider a fictional single U.S. taxpayer born in 1980, original sole owner of a Series EE bond issued in 2010. They redeemed it in 2025 for $12,000: $8,000 principal and $4,000 interest, never previously reported annually. This was their only savings-bond redemption that year.
In 2025 they paid $9,000 required tuition for their own degree program at an eligible U.S. college. No refunds, tax-free educational assistance, education credits, 529/Coverdell distributions or other adjustments apply. Their correctly computed education-bond MAGI is $60,000 before this exclusion, below the 2025 single phaseout range.
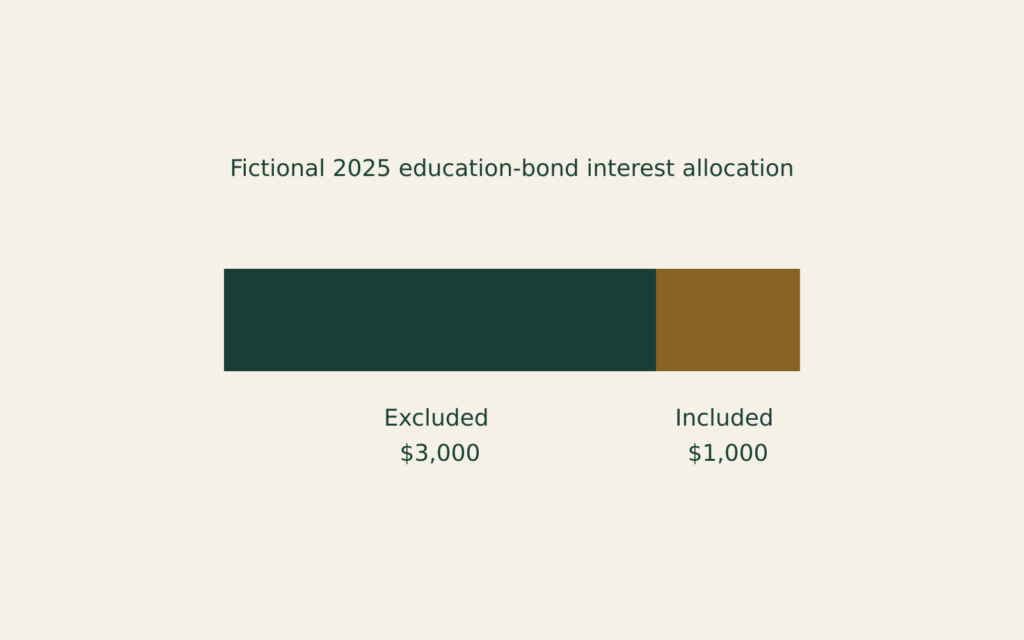
IRS Publication 970 applies the expense/proceeds fraction: $4,000 × ($9,000 ÷ $12,000) = $3,000 excluded interest. The remaining $1,000 is included in income—not $1,000 tax owed.
Tuition exceeding the $4,000 interest does not exclude all interest: the denominator also includes principal. Match the issue/ownership records, redemption breakdown and eligible payments before reconciling the exclusion.
Insurance Gain and Replacement Basis
Reconcile replacement spending and postponed gain.
Foreign Income: Two Periods
Reconcile qualification and annual proration.
Earned Income Credit: Two Lookups
Compare earned income and AGI.