Enterprise Value and Funding
Reconcile acquisition funding.
Estimated reading time: 1 minute
FINRA explains enterprise value as equity value plus debt minus cash. Equity value is not the entire acquisition’s funding requirement.
Fictional acquisition: enterprise value is $500,000, debt $120,000 and cash $40,000. Assume only common shares and debt repayable at its stated amount.
Equity value is $500,000 − $120,000 + $40,000 = $420,000. Stipulate that this is the agreed payment to existing shareholders—not money raised by the company.
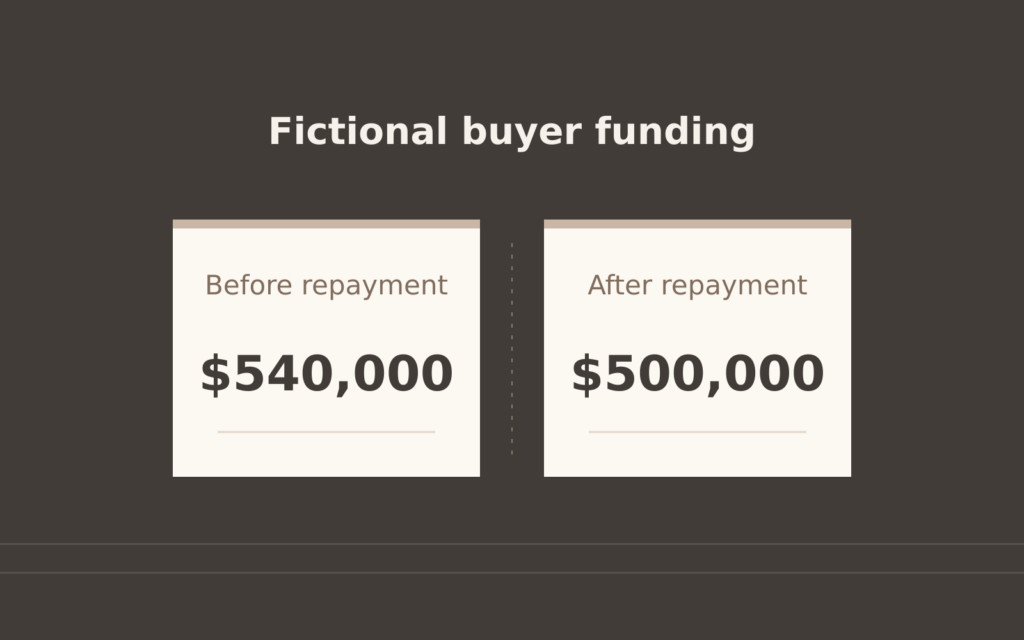
If the buyer pays shareholders and retires debt before accessing acquired cash, gross funding is $420,000 + $120,000 = $540,000. Accessing $40,000 produces a $500,000 net outlay. That later cash cannot fund an earlier payment.
Alternatively, suppose the company uses its $40,000 to repay debt. Debt becomes $80,000 and cash zero. Equity value remains $420,000; gross funding becomes $500,000, with no cash left to subtract.
These are alternative records, not cumulative payments. Confirm contractual debt, cash, timing and operating-reserve requirements. The model excludes fees, taxes, working-capital adjustments and financing costs; it establishes neither an appraisal nor permission to use company cash.