Foreign Tax Credit Limit
Reconcile foreign tax and limits.
Estimated reading time: 1 minute
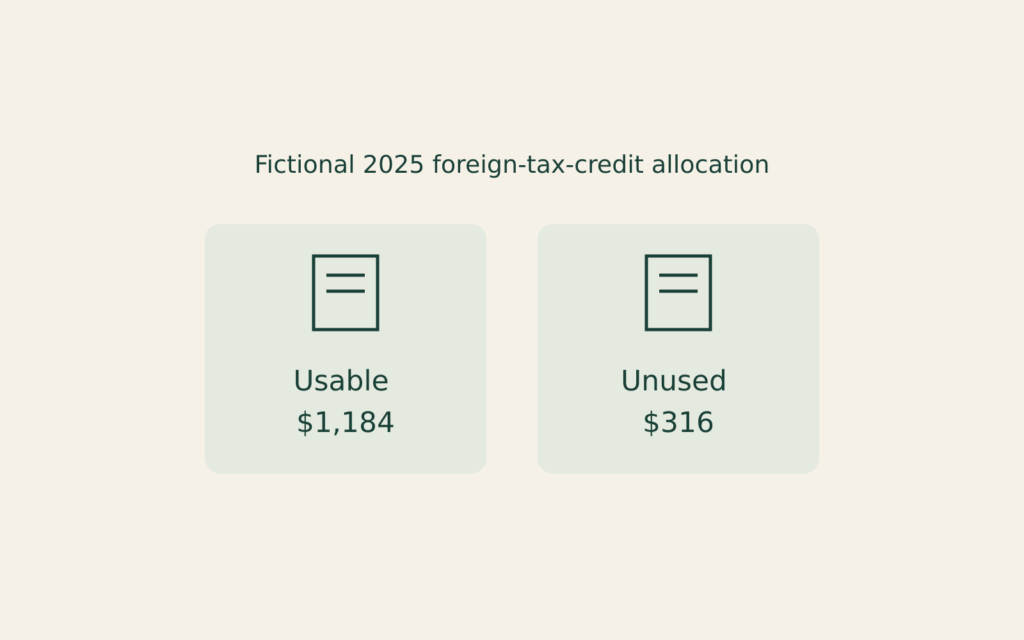
Creditable foreign tax can exceed the amount usable on the current U.S. return.
Consider a fictional single U.S. citizen’s ordinary 2025 wages. Independently verified foreign-tax-credit inputs are $50,000 worldwide taxable income, including $10,000 foreign-source taxable employment income after required deduction allocation, and $5,920 applicable U.S. income tax before this credit.
They chose the credit and paid $1,500 of qualifying foreign income tax on that employment income. It is their only foreign income category, correctly classified as general category. No foreign-income exclusion, preferential-rate income, treaty resourcing, loss adjustment, prior credit carryover, other credit or special adjustment applies.
IRS Publication 514 limits this credit to the applicable U.S. tax times the foreign-source share: $5,920 × ($10,000 ÷ $50,000) = $1,184. That is less than $1,500, so $1,184 is currently usable; $316 is not.
Match income sourcing, deduction allocations and creditable-tax records. The $316 is not an automatic refund or additional current deduction; this example does not determine carryback, carryforward or the final return balance.
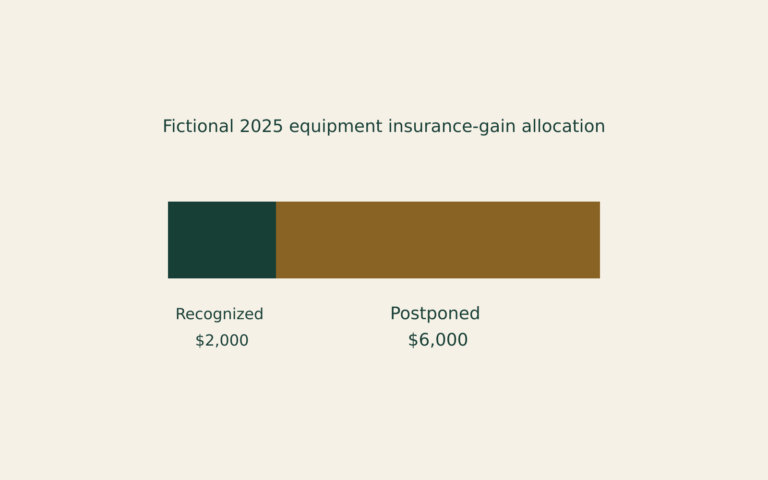
Insurance Gain and Replacement Basis
Reconcile replacement spending and postponed gain.
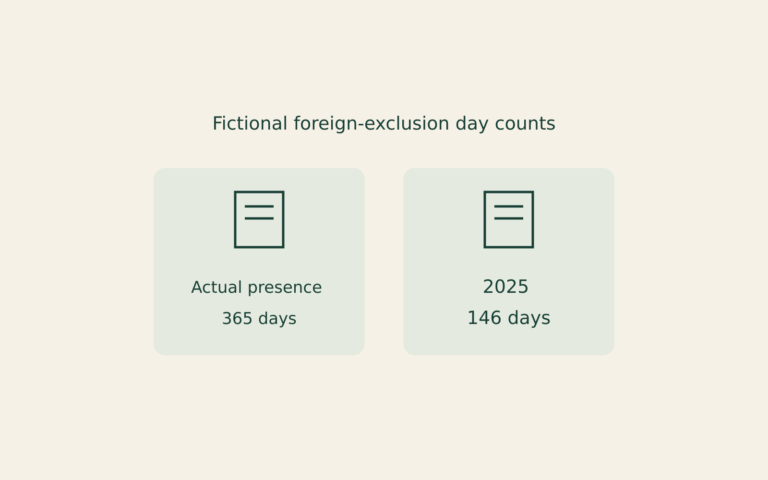
Foreign Income: Two Periods
Reconcile qualification and annual proration.
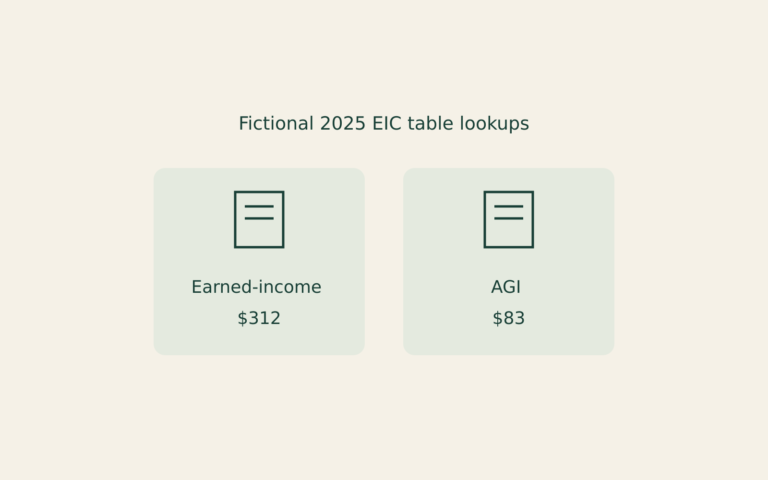
Earned Income Credit: Two Lookups
Compare earned income and AGI.