Mileage Deductions and Vehicle Basis
Separate deduction and depreciation.
Estimated reading time: 1 minute
A standard-mileage deduction includes depreciation, but the entire deduction does not reduce the car’s tax basis.
A fictional U.S. sole proprietor buys a car for $30,000 cash in January 2024 and immediately uses it exclusively for business. It is their only business vehicle. They timely choose standard mileage in 2024 and continue it in 2025, never claiming actual expenses, section 179 or bonus depreciation. Complete logs establish 10,000 business miles each year, with no commuting or personal use.
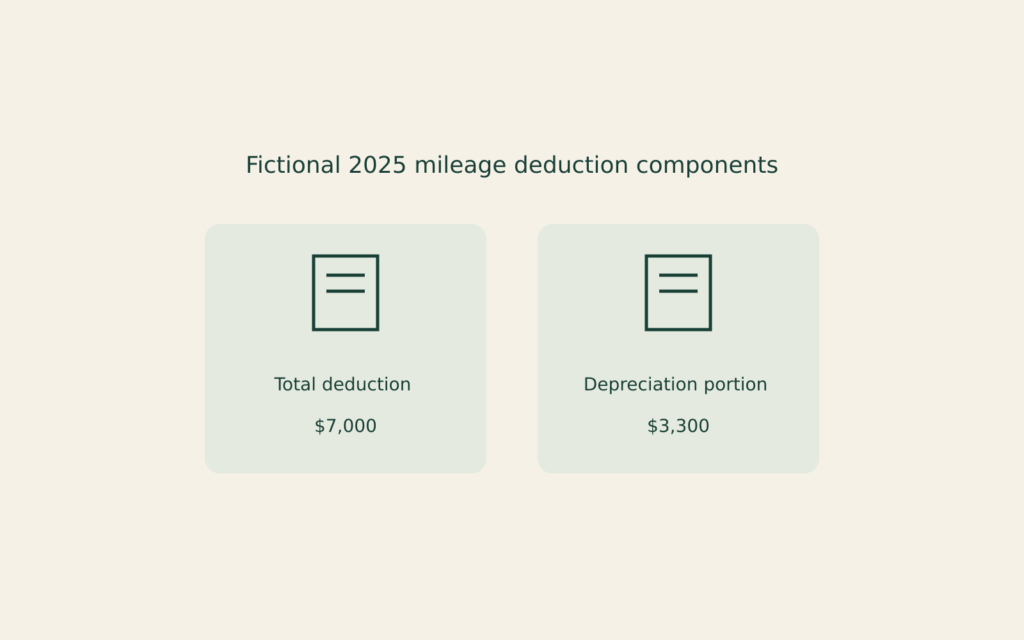
Under Publication 463, 2025’s mileage deduction is 10,000×$0.70=$7,000. Its depreciation component is only 10,000×$0.33=$3,300. The 2024 component is 10,000×$0.30=$3,000.
With no other basis adjustments, cumulative depreciation is $6,300 and adjusted basis is $30,000−$6,300=$23,700.
After those miles, an unrelated buyer pays $25,000 cash on December 31, 2025. There are no selling expenses, debts or other consideration. Gain is $25,000−$23,700=$1,300, treated as ordinary depreciation recapture—not a $5,000 deductible loss from comparing price with original cost. Final tax remains separate.
Mid-Quarter Depreciation Across Purchases
Check the entire acquisition pool.
Alternative Minimum Tax Reconciliation
Separate tentative and additional tax.
Self-Employed Health Insurance Limits
Check coverage eligibility before enrollment.