Travel Insurance: A Medical Waiver Is Not CFAR
Separate an exclusion waiver from broader cancellation protection.
Estimated reading time: 9 minutes
U.S. educational comparison. This page isn’t a provider recommendation, medical assessment or claim decision. Read the policy offered for your state and trip; examples don’t establish coverage.
The word “waiver” can appear in several parts of a travel offer. Before comparing prices, identify exactly what is being waived and by whom. An insurer removing a medical exclusion, a CFAR endorsement and a travel supplier waiving a cancellation fee are different arrangements.
Compare a travel insurance waiver, CFAR and supplier remedies
| Feature | Question it addresses | What it does not establish |
|---|---|---|
| Standard trip cancellation | Is my reason for canceling among the policy’s covered reasons? | Coverage for every possible change of plans. |
| Medical exclusion waiver | Can the specified pre-existing-condition exclusion be removed from applicable benefits? | A new right to cancel for any unrelated reason. |
| CFAR | Can I receive partial reimbursement when my cancellation reason is outside standard coverage? | A full refund, unlimited timing or automatic eligibility. |
| Supplier cancellation-fee waiver | Will the travel seller waive a fee under its own agreement? | That the arrangement is insurance or covers all other trip purchases. |
The NAIC’s travel-insurance overview distinguishes insurance from non-insurance cancellation-fee waivers and assistance services, even when sold in one package. It describes CFAR as partial reimbursement subject to conditions such as timely purchase, insured trip costs and cancellation restrictions.
Use the table to identify your concern before selecting a product. “I need to cancel because I no longer want to travel” is a different question from “A condition I already had may affect a benefit that otherwise covers this event.”
Travel insurance waiver: what the medical exclusion changes
Start with a covered benefit, then examine its exclusions. A waiver can remove a specified obstacle, but the remaining benefit rules still matter: the event, covered person, eligible expense, documentation and limits all need to fit.
As a provider-specific example, Travel Guard’s medical waiver guide describes removing the pre-existing medical condition exclusion from applicable coverage. Its stated requirements include buying within the initial-trip-deposit window, insuring all prepaid nonrefundable costs and timely additions, and being medically able to travel when purchasing. The offered plan may specify the applicable period and conditions.
Don’t reduce this to “I bought travel insurance early, so every health-related cancellation is covered.” Ask which benefits the waiver modifies and what remains excluded. If the concern involves another person, ask whether that person’s circumstances fall within the policy’s definitions rather than assuming every relative is treated alike.
For a medical issue during travel, care needs come first. Use the assistance and claims instructions in your actual policy. This article can’t tell you whether a condition meets the insurer’s definition or whether you’re medically able to travel.
What CFAR changes
CFAR addresses the cancellation reason more broadly, while preserving other requirements. A qualifying cancellation may still leave you responsible for a substantial part of the trip cost. Purchase timing and cancellation timing are two separate deadlines.
Travel Guard’s CFAR guide, used here only as one example, describes an optional add-on on eligible plans. It states that it must be selected with the base plan within 15 days of the first trip payment and can reimburse up to 50% of insured trip costs, subject to terms and state availability.
That guide uses both “more than 48 hours” and “at least 48 hours” wording for cancellation. Obtain the exact cutoff in your policy and written clarification where needed; don’t plan around the boundary based on a marketing summary. Other providers and plans can have different percentages and windows.
Worked example: a $5,000 trip and partial reimbursement
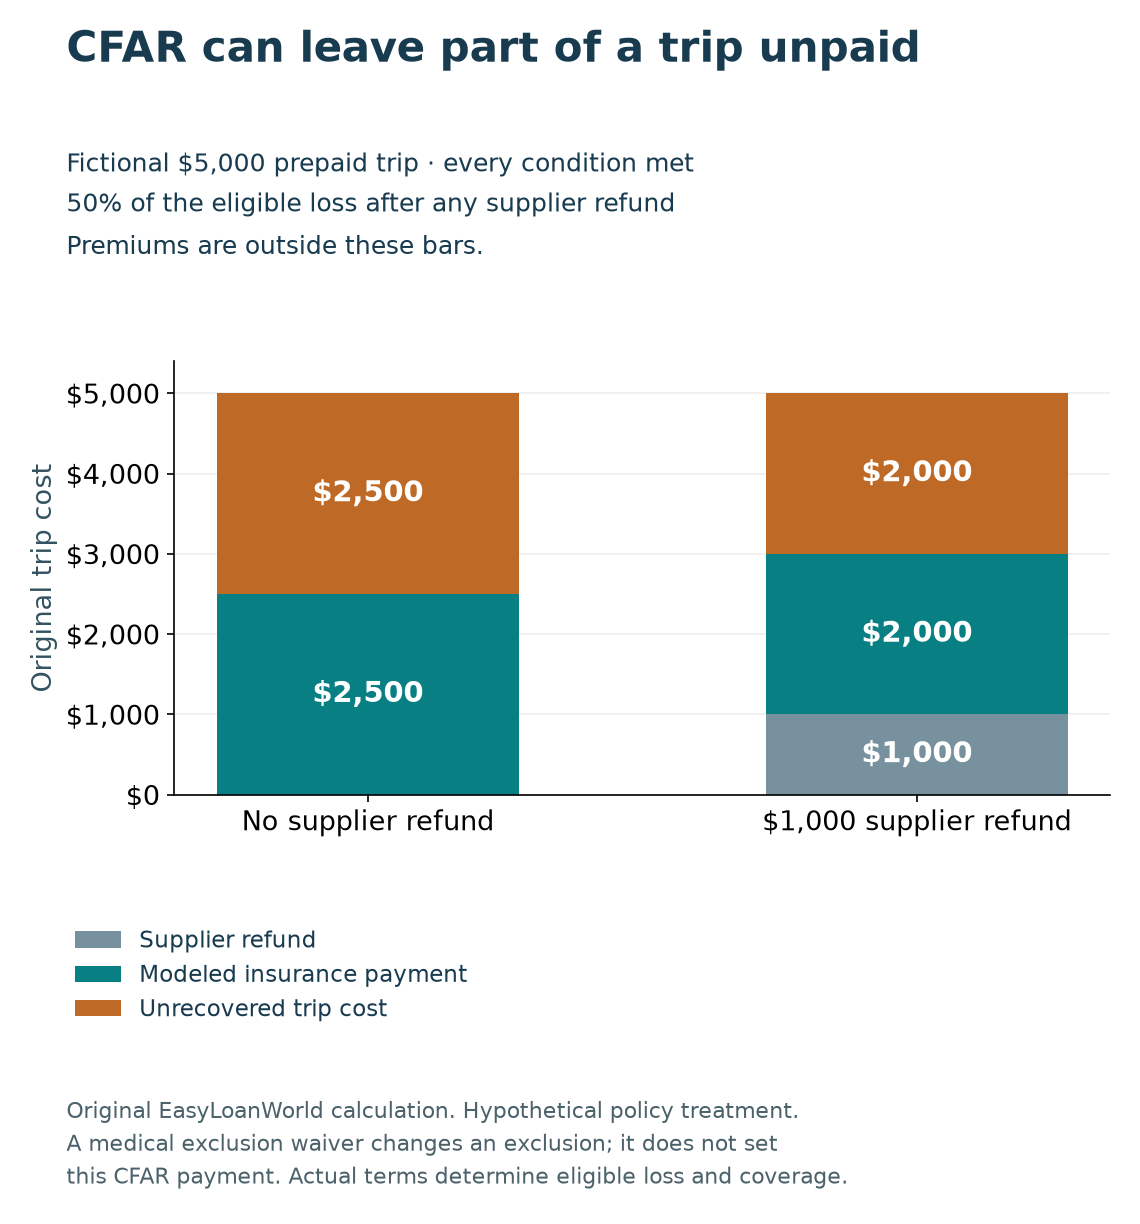
Assume a fictional trip has $5,000 of eligible prepaid, nonrefundable costs. The traveler has a valid CFAR benefit paying 50%, meets every condition and cancels within the required window. Ignore premiums, other refunds, credits and adjustments in this first example.
| Item | Amount |
|---|---|
| Eligible nonrefundable trip costs | $5,000 |
| Assumed reimbursement percentage | 50% |
| Illustrative reimbursement | $5,000 × 50% = $2,500 |
| Unreimbursed eligible trip costs | $5,000 − $2,500 = $2,500 |
A “cancel for any reason” label does not turn this into a $5,000 refund. If the hypothetical insurance premium were $300 and not refunded, the traveler’s total unrecovered cash in this simplified scenario would be $2,500 + $300 = $2,800.
Now change one assumption. Suppose the supplier refunds $1,000 and the policy treats the remaining $4,000 as the eligible unrecovered loss. At the stipulated 50%, insurance would pay $2,000. Total recoveries would be $3,000, leaving $2,000 of trip costs unrecovered before premiums. This second calculation depends on the assumed policy treatment; your insurer must confirm how refunds and travel credits affect a real claim.
The useful calculation is therefore based on eligible unrecovered costs, not automatically the largest number printed on the booking confirmation.
Match the concern to the relevant wording
| Concern | What to read first |
|---|---|
| A health event may prevent travel | Covered cancellation reasons, medical definitions, evidence requirements and any relevant exclusion waiver. |
| You simply prefer not to take the trip | Whether CFAR was purchased, its cancellation deadline and reimbursement terms. |
| The airline cancels the flight | The airline’s refund obligations and your payment options, then the insurance terms for any remaining loss. |
| You want to change dates instead of canceling | The supplier’s change rules and the exact policy benefit; do not treat date changes as automatically covered by CFAR. |
| The seller advertises a “waiver” | The agreement identifying the provider, fee or exclusion waived, and available remedy. |
These questions help you collect the right facts without pretending that a short scenario can determine a claim. Coverage may turn on definitions or conditions that aren’t visible in a quote comparison.
Travel insurance waiver and CFAR: seven purchase checks
- List every trip payment. Record supplier, payment date, amount and whether it’s refundable. Identify the first trip deposit accurately.
- Write down the concerns you want covered. Use specific situations, such as an ongoing medical condition or a possible change of plans, instead of “full coverage.”
- Request the offered policy. Obtain the schedule of benefits and endorsements for your state, not only a general product page.
- Check the medical waiver separately. Confirm eligibility, purchase window, insured-cost requirements, applicable benefits and treatment of later trip additions.
- Check CFAR separately. Confirm it’s actually selected and identify the purchase deadline, cancellation cutoff, percentage and eligible expenses.
- Compare with supplier remedies. Record possible cash refunds, credits and fee waivers, and ask how the policy treats them. Don’t assume insurance pays the same loss twice.
- Save the evidence. Keep the application, policy, payment receipts, answers to material questions and cancellation instructions in one place.
A useful written question is: “For the scenario described below, which benefit would apply, which exclusion or waiver matters, what deadline must I meet and what documents would you require?” Ask the insurer to identify the policy section rather than relying on a general assurance.
Record the travel insurance waiver and CFAR requirements separately
Use one dated trip-cost list and separate rows for the medical waiver and CFAR. Record the triggering event, exact deadline wording, relevant policy section and evidence that any required action was completed. A travel insurance waiver’s purchase condition and CFAR’s cancellation cutoff answer different questions; one date shouldn’t silently replace the other.
Consider a fictional record with an initial trip payment on day 1, policy purchase on day 8 and a further nonrefundable booking on day 30. These dates are an organizing example, not an eligibility calculation. Ask the insurer which initial-payment rule applies, how the later booking must be reported and insured, and what dated document will confirm the change.
| Event or condition | Evidence to keep |
|---|---|
| First trip payment | Supplier receipt and actual payment date |
| Medical waiver requirements | Applicable benefit, conditions and relevant policy wording |
| CFAR selected | Schedule or endorsement showing the optional benefit |
| Later trip cost added | New receipt and insurer’s confirmed update instructions |
| Cancellation cutoff | Exact time reference, departure details and required notification channel |
For example, if receipts now total $6,000 while the policy schedule still shows $5,000, identify the $1,000 difference and obtain instructions promptly. Don’t assume the new expense is automatically insured or that the mismatch alone determines the result of a future claim.
Keep the travel insurance waiver’s conditions separate from medical judgments and coverage decisions. The insurer must explain the offered wording, while a clinician addresses medical ability to travel where relevant. Record an answer as a specific condition clarified, rather than “everything covered.” This makes later changes easier to check without turning a marketing phrase into a blanket promise.
Frequently asked questions
Can I have both a medical waiver and CFAR?
Some offered plans may allow both, but confirm availability and qualify separately for each. They address different issues; one doesn’t prove the other is included.
Does a medical waiver mean my condition is covered in every situation?
No. It removes the specified exclusion from applicable benefits under its terms. The rest of the benefit definitions, limits and claims requirements remain relevant.
Does CFAR mean I can cancel immediately before departure?
Don’t assume that. CFAR can require cancellation a specified time before departure. Use the exact policy wording and obtain clarification before relying on an ambiguous cutoff.
Should I use a travel credit before contacting the insurer?
First understand the supplier’s options and ask how each affects the insurance claim. A refund, credit and nonrefundable loss are different amounts in the calculation. Keep the offer and your response documented.
Next step: Make a one-page trip-cost list and compare each concern against the offered policy. For separate payment questions, see canceled-flight refunds versus airline credits and hotel card holds and checkout payments.
Sources checked October 25, 2026. Figures are hypothetical. Provider examples aren’t endorsements, and no professional claim review is implied.


Roth Conversion and Account Clocks
Separate five-year tests.

ABLE Distributions Across Month-End
Separate retained purposes.