Payday Alternative Loans: Your Options
Screen three cash needs, then compare actual offers.
Federal credit unions may offer payday alternative loans. Ask which type is available and whether you can join. Similar advertising language does not establish a regulated PAL. See NCUA’s overview and consumer guidance.
Match the amount and repayment window
| Program | Amount | Term | Membership |
|---|---|---|---|
| PAL I | $200–$1,000 | 1–6 months | At least one month |
| PAL II | Up to $2,000 | 1–12 months | No corresponding waiting period |
Both fully repay principal through installments. Application charges must reflect processing costs, capped at $20. NCUA rule.
Try three different requests
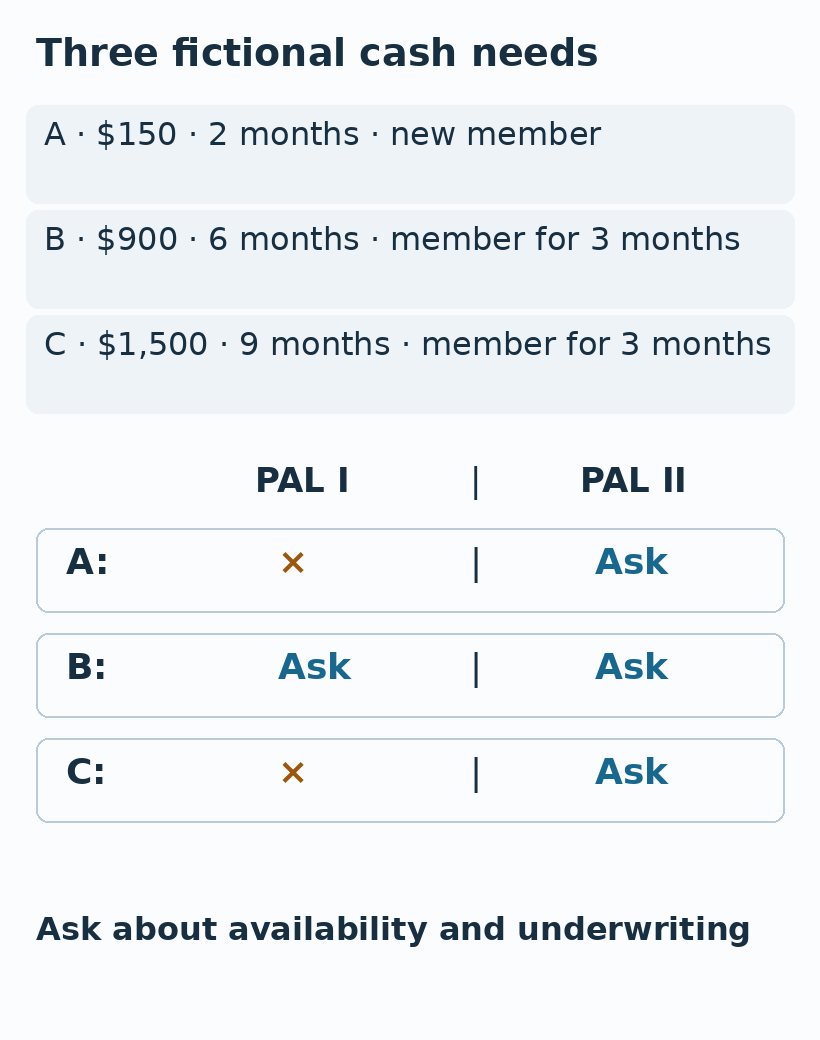
The people and cash needs below are invented. Each requests exactly the amount and term shown. Only amount, term and membership are screened here.
| Fictional request | PAL I | PAL II |
|---|---|---|
| A: New member; $150 over two months | Excluded: amount and membership | Ask |
| B: Three-month member; $900 over six months | Ask | Ask |
| C: Three-month member; $1,500 over nine months | Excluded: amount and term | Ask |
“Ask” means check availability and the credit union’s underwriting; it is not approval. Passing a program screen does not establish that the payments fit your finances.
Do not increase a $150 need simply to meet a product minimum. Start with the amount actually needed and the cash you can return on the proposed dates. If you are choosing between two real offers, complete the comparison below with those offers rather than with a program’s maximum amount.
Compare the actual cash and payments
NCUA’s active rate letter preserves the PAL interest ceiling of 28% alongside the ordinary ceiling extended through September 10, 2027. Request the disclosed APR and itemized charges; do not assume the stated interest rate includes an application charge.
| Compare | Offer A | Offer B |
|---|---|---|
| Cash you would actually receive | _____ | _____ |
| Each installment and its due date | _____ | _____ |
| Total scheduled repayments | _____ | _____ |
| Application charge; paid separately or deducted? | _____ | _____ |
| Quoted interest rate and disclosed APR | _____ | _____ |
Ask which line already includes each charge before adding totals. A deduction changes spendable cash; a separate charge needs cash of its own. For uncertain paydays, the variable-income payment-calendar example helps test whether money is available on the actual due date.
Use the program screen to choose where to inquire, then decide whether a specific written offer solves the shortage without creating another one. U.S. educational information, checked October 19, 2026; not an individual lending recommendation.
Keep Savings or Pay Extra on a Personal Loan? Compare Cash and Debt
A fictional three-payment comparison shows how extra principal changes cash, debt, and interest, then tests which expenses the remaining cash can cover.
Stop Loan Autopay: Separate the Debit From the Debt
Review a fictional $210 payment, trace a $420 cash outflow, and compare the supporting records before treating an unexplained difference as resolved.
Personal Loan Late Payments: Verify the Catch-Up Amount
Organize a dated payment record, separate the next installment, and check a fictional catch-up calculation against the lender’s response.